Quick Answer
A butterfly is a three-strike, four-leg position whose payoff is a tent: it pays most if the underlying finishes at the middle strike and its loss is fixed at the wings. The version a premium seller actually meets is the iron butterfly — a short at-the-money straddle with an out-of-the-money call and put bought equidistant on either side. It is the defined-risk form of a short straddle. You keep the tent-shaped profit, you give up part of the credit, and you buy a hard ceiling on the loss. What you do not buy is relief from gamma near expiry, and in our own testing the defined-risk version of a losing structure lost more, not less.
Three things the broker explainers usually skip, all covered below: the break-even range of a typical iron butterfly sits inside the move the options market is already pricing, four legs cost real money to trade, and on NIFTY and SENSEX the early-assignment worry you read about in US guides does not exist, because index options settle in cash at expiry.
Paper trade every structure in this piece before it touches live capital. Nothing below is investment advice — it is how we price and reject these structures on our own desk, and it is analysis, not a signal. If you are new to option selling, start with the Nifty option selling guide for beginners.

Three different things are called a "butterfly"
This is the first place the term costs people money, because a long call butterfly and an iron butterfly have nearly the same payoff picture but opposite cash flows, and the word "butterfly" on a broker screen does not tell you which one you are looking at.
| Name | Legs (equally spaced strikes K1 < K2 < K3) | Net cash at entry | Wins when |
|---|---|---|---|
| Long call butterfly | Buy 1 call at K1 · sell 2 calls at K2 · buy 1 call at K3 | Debit — you pay | Spot finishes at or near K2 |
| Short call butterfly | Sell 1 call at K1 · buy 2 calls at K2 · sell 1 call at K3 | Credit — you receive | Spot finishes outside K1 or K3 |
| Iron butterfly | Sell 1 call + 1 put at K2 (the straddle) · buy 1 put at K1 · buy 1 call at K3 | Credit — you receive | Spot finishes at or near K2 |
Read the two right-hand columns together and the useful fact drops out: the long call butterfly and the iron butterfly want the same outcome — a pin at the middle strike — but one pays a debit to get there and the other collects a credit. Their payoff diagrams are the same tent. They are, in pricing terms, the same position reached from two directions. The short call butterfly is the odd one out: it is a bet on a large move, which is the opposite of what a premium seller is doing.
So when an option seller says "butterfly", the structure in play is almost always the iron butterfly, and the rest of this page is written from that side.
One payoff, four ways to build it
The tent can be built four ways: all calls, all puts, a mix of a call spread and a put spread for a debit, or the iron version for a credit. At expiry they pay out almost the same, because put-call parity keeps the equivalent call and put combinations priced in line; if one were clearly cheaper, traders would arbitrage the gap away. The difference is what happens before expiry: how much cash you put up, how much margin the broker blocks, and how the position reacts to time and volatility. The all-call and all-put versions are debit trades where the most you can lose is what you paid. The iron version is a credit trade, so the broker blocks margin against the width of the wings instead. For a seller who is already collecting premium, that credit form is the natural one, which is why the rest of this page uses it.
The payoff arithmetic, done once
Take an illustrative NIFTY chain with spot at 24,850, and build an iron butterfly on the 24,850 strike with 200-point wings. The numbers below are round illustrative premiums, not a quoted chain — the point is the arithmetic, which does not change.
- Sell the 24,850 call at ₹95
- Sell the 24,850 put at ₹88
- Buy the 25,050 call at ₹31
- Buy the 24,650 put at ₹27
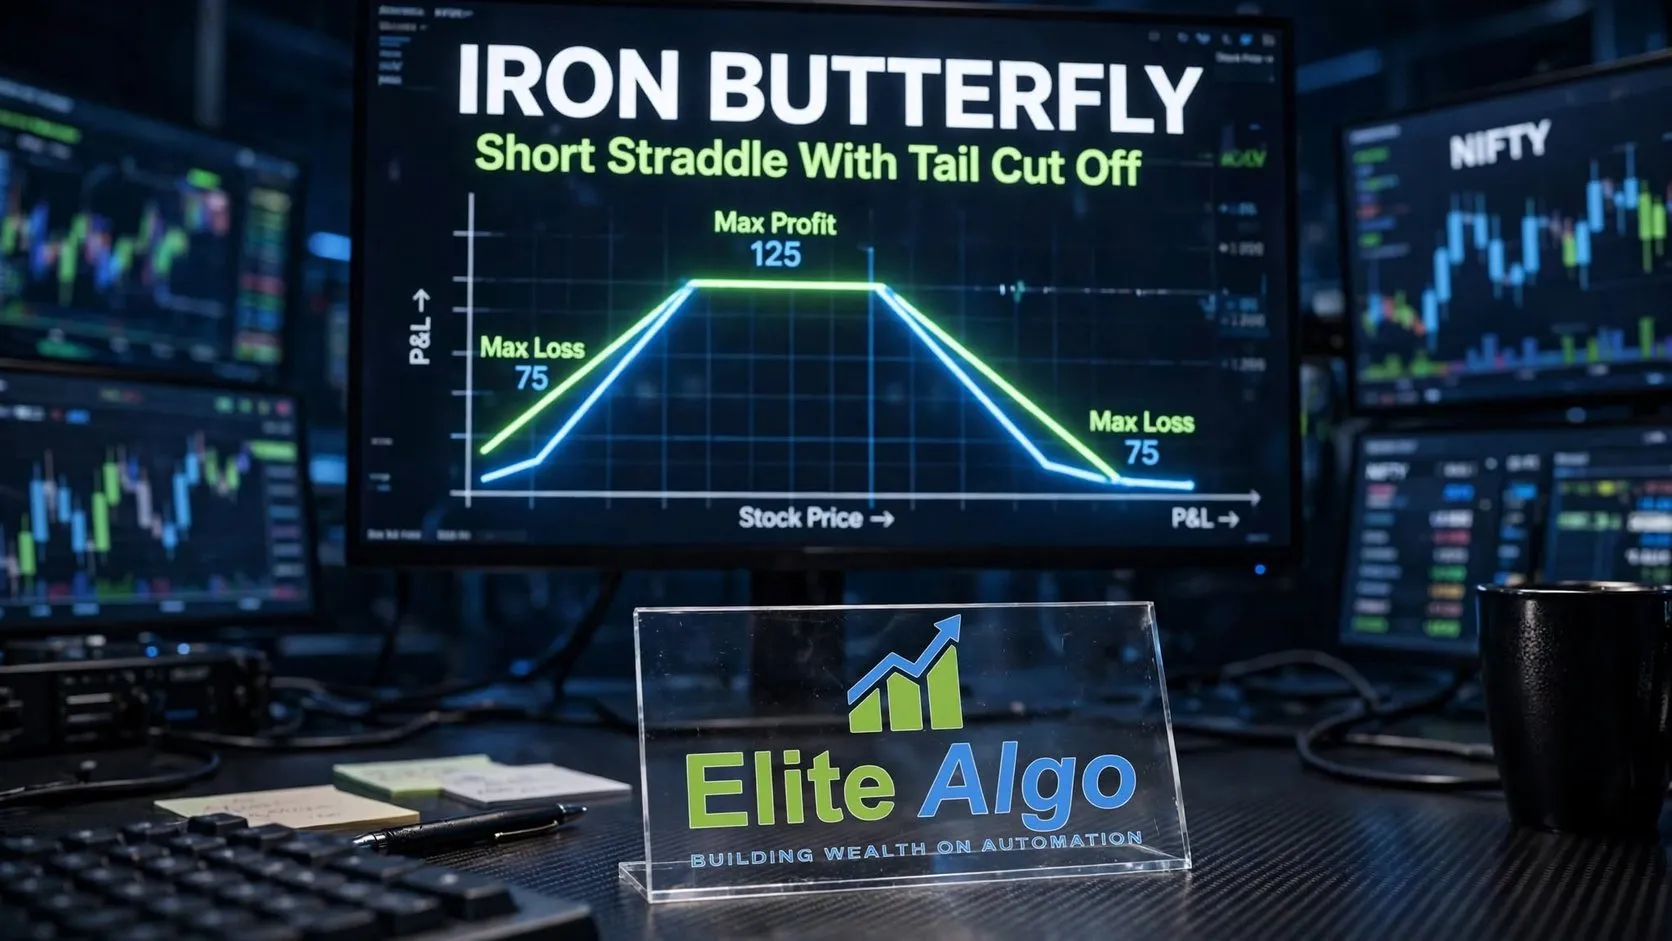
Net credit = (95 + 88) − (31 + 27) = ₹125 per unit. That ₹125 is the maximum profit, and it is only collected in full if NIFTY expires exactly at 24,850.
Maximum loss = wing width − net credit = 200 − 125 = ₹75 per unit. That is the entire downside, known at entry, whatever happens to the index. Multiply by your current NIFTY lot size to get the rupee figure for one lot — and check the lot size against NSE's current contract specifications rather than a number you remember, because it gets revised.
Breakevens = middle strike ± net credit = 24,850 ± 125, so 24,725 and 24,975. That is a 250-point window on an index trading at 24,850 — roughly 1%. Outside it you are losing; 200 points out on either side you are at the full ₹75.
Now compare the same four legs to the naked short straddle inside them. The straddle alone collects ₹183 instead of ₹125, and its breakevens are 24,667 and 25,033 — a 366-point window, nearly 50% wider. The wings cost you ₹58 of credit and 116 points of breakeven room. In exchange they cap the loss at ₹75 instead of leaving the call side open.
Now put it in rupees. NIFTY's lot size is 65 at the time of writing (see our lot size guide; NSE revises it from time to time, so confirm before you trade). One lot of this butterfly has a maximum profit of 125 × 65 = ₹8,125 and a maximum loss of 75 × 65 = ₹4,875, before brokerage, taxes and slippage. On paper that is a reward-to-risk of about 1.7 to 1, which is exactly why these look attractive on a payoff chart.
Here is the part the chart does not show. The 24,850 straddle in this example costs ₹183, and the price of an at-the-money straddle is a rough read of how far the market expects the index to move by expiry. Your breakevens are only 125 points out. So the butterfly asks the index to finish inside a range that is narrower than the move the market is already charging you for. A 1.7-to-1 payoff that needs that is not generous; it is the price of a low hit rate. Before entering any iron butterfly, compare the credit with the straddle price. The smaller the credit is as a share of the straddle, the further your breakevens sit inside the expected move.
That is the whole trade in one line: you are paying about a third of your credit, and a third of your profit range, for a known worst case. Whether that is a good price depends entirely on how often the worst case shows up in your own data — not on how it feels.
Why the iron butterfly is a short straddle with the tail cut off
Strip the wings out of an iron butterfly and you have an at-the-money short straddle, which is the structure our short straddle vs short strangle comparison works through in detail. Everything that makes a short straddle hard still applies: both legs sit at the money, so they carry the highest extrinsic value and the highest theta on the chain, and they also sit with zero directional cushion. The wings change one thing only — how bad it gets when you are wrong.
The sequence is worth being precise about, because it is what actually happens to the position intraday rather than at expiry:
- Spot drifts away from the middle strike. The short leg on that side starts gaining value against you while the short leg on the other side decays in your favour. Net, you are losing.
- As spot approaches the wing strike, the long option on that side starts to respond and begins offsetting the short leg. This is the first point at which the structure does anything for you.
- Past the wing strike, the long and short move point-for-point and the loss stops growing. You are at maximum loss and it will not get worse.
Note where the protection lives: at the wings, not in between. Through the entire region where most sessions actually resolve, the long options are doing almost nothing except having cost you money. That is not a flaw in the structure; it is what you bought. But it means the wings are insurance with a deductible, and the deductible is 200 points wide.
The Greeks of an iron butterfly, side by side
| Greek | Sign | What it means in practice |
|---|---|---|
| Theta (time decay) | Positive | The two short at-the-money options lose value faster than the two cheap wings. This is where the credit comes from, and it is strongest in the last hours of expiry day. |
| Delta | Near zero at entry | Neutral when the index is at the middle strike. It turns against you the moment the index drifts, and drifts faster than most beginners expect. |
| Vega | Negative | You gain if implied volatility falls and lose if it rises. The wings reduce this a little but do not remove it. |
| Gamma | Negative, large near the strike | The short legs are at the money, so delta changes fastest exactly where you are. The wings only start to help once the index is near them. |
Several broker guides describe the iron butterfly's gamma exposure as "limited" next to a naked straddle. That is true for the final loss, which is capped. It is not true for the speed of the move on the way there, and expiry afternoon is when that speed matters. We come back to this in the gamma section below.
How we would set one up, step by step
This is the order we work through when we price a butterfly for study. It is a checklist for analysis, not a signal and not a recommendation to trade.
- Pick the expiry and the day. An iron butterfly is a time-decay structure, so it is usually looked at for the current weekly or the day of expiry. Shorter time means faster decay, and also faster gamma.
- Choose the middle strike. At the money, the strike nearest to the index, for the standard version. Moving it away adds a directional lean you should be able to defend.
- Price the straddle first. Note the combined call and put premium. That is your reference for the market's expected move.
- Choose the wing width. Narrow wings cap the loss tightly but give back more of the credit. Wide wings keep more credit but allow a bigger loss and use more margin. Compute the credit as a share of the wing width and of the straddle before you decide; in our example the credit is 125 on a 200-point wing, which is 62.5% of the width.
- Send the bought wings first. Place the two long options before the two short ones so the position is never briefly naked and the broker's margin engine sees the hedge. Check how your own broker's basket order sequences the legs; do not assume.
- Check margin on your broker's calculator before you confirm. See our notes on SPAN and exposure margin and the gap between the NSE calculator and your broker's number.
- Write the exit before you enter. Total-loss stop, a clock exit, and a profit-taking level. More on this below.
Margin and capital: where the wings genuinely help
Here the wings earn their cost. A short straddle has open-ended risk on the call side, so the broker blocks a large SPAN-plus-exposure figure against it. Add the two bought wings and the risk engine sees a capped position, so the blocked amount falls a lot. For a smaller account that cannot comfortably carry a naked straddle through a volatile session, that is a real reason to use the iron form. How large the saving is depends on the wing width and on the exchange's volatility parameters for the day, so read it from the margin calculator rather than from any percentage in an article. We worked through the same trade-off for the strangle in iron condor vs naked strangle, and the two hedge tools we actually use are in when and how we hedge a naked strangle.
Iron butterfly vs iron condor — the only comparison that matters for us
Both are defined-risk premium structures. The difference is where the short legs sit.
| Factor | Iron butterfly | Iron condor |
|---|---|---|
| Short legs | Both at the same ATM strike | Split, both OTM |
| Underlying naked structure | Short straddle | Short strangle |
| Credit collected | Higher | Lower |
| Profit window | Narrow — peaked at one strike | Wide and flat between the shorts |
| Probability of finishing at full profit | Low — needs a pin | Higher, but pays less |
| What it is really betting on | Realised move smaller than implied, centred | Realised move staying inside a range |
The butterfly is the more aggressive of the two. It collects more and demands more: not just a quiet session, but a quiet session that ends near where it started. If you believe the index pins, the butterfly is the structure that pays you for being right about it. Our own work on that assumption is in max pain on NIFTY, where we tested the pin everyone quotes — and the short version is that the pin is far less reliable than the folklore around it suggests, which is a direct argument against paying for a narrow tent.
The condor's wide flat top is why it gets recommended more often. It is also why it collects less. There is no free lunch in the shape.
Side by side with the two naked versions, since that is the choice most sellers are really making:
| Short straddle | Iron butterfly | Short strangle | Iron condor | |
|---|---|---|---|---|
| Short strikes | Same ATM strike | Same ATM strike | Two OTM strikes | Two OTM strikes |
| Bought wings | None | Yes, both sides | None | Yes, both sides |
| Maximum loss | Open-ended on the call side | Wing width minus credit | Open-ended on the call side | Wing width minus credit |
| Credit | Highest | High, less the wings | Medium | Lowest |
| Profit window | Narrow | Narrowest | Wide | Wide, flat |
| Legs to trade | 2 | 4 | 2 | 4 |
| Margin blocked | High | Much lower than the straddle | High | Much lower than the strangle |
Our desk-level reasoning for choosing between the left and right columns is in short straddle vs short strangle and iron condor vs naked strangle.
What our own testing found — and it is a negative
We do not have a profitable butterfly or iron butterfly configuration to show you, and we are not going to imply one exists. Here is what our research actually measured.
When we ran a technical-signal-driven option-selling engine across 438 trading days, selling a short strangle on the signal lost money at zero slippage. We then ran the defined-risk version of the same idea — an iron condor instead of the naked strangle — on the same signal and the same days. It lost more, not less. Across a wider sweep of eighteen structure-and-parameter combinations covering naked and defined-risk variants, none passed our acceptance gate.
That result is worth more than another explainer of the payoff diagram, because it names the mistake the structure invites. Capping the tail does not fix a structure whose edge is negative in the middle. The wings cost real premium every single cycle. If the thing inside the wings does not make money, buying insurance on it makes the arithmetic worse, and it does so quietly — a defined-risk position that bleeds slowly feels safer than a naked one that occasionally lurches, right up until you total the year.
The second number from our own book points the same way. Across 163 logged expiry sessions, the median give-back from a session's intraday profit peak to its close was 42.8%, and about 30% of sessions turned a position that had been profitable at its peak into a loss by the close. A narrow tent is the structure least tolerant of that behaviour: an iron butterfly needs the index to be near one strike at the close, and nearly a third of our sessions ended somewhere materially worse than where they had already been.
Gamma does not go away because the loss is capped
This is the single most common misreading of defined-risk structures, and it is the same point we make about credit spreads: a cap on size is not a cap on speed.
Both short legs of an iron butterfly sit at the money. At the money, on expiry day, is exactly where gamma is largest — the position's directional exposure changes fastest per point of index move, and it changes fastest in the final hours. The wings fix how much you can ultimately lose. They do nothing about how quickly the position can travel from comfortable to maximum loss, which on an expiry afternoon can be a single twenty-minute stretch. Our walkthrough of the Greeks on expiry day covers why theta stops being the story after about 2 PM and gamma takes over; an ATM-shorted butterfly is the structure most exposed to that handover.
Practically: a defined-risk position still needs a stop rule and a square-off time. "Max loss is known" is not a risk plan. It is a number you have agreed to accept, and you should decide in advance whether you actually want to accept it or would rather exit before it.
The execution cost nobody prices in
A butterfly is four legs. Every structural comparison you will read online ignores what that means at the order book. Our guide on how to backtest an option-selling strategy shows how to model the cost of four legs.
- Four bid-ask spreads, not one. You cross the spread four times entering and up to four times exiting. On the wings — which are further out of the money and thinner — the spread is proportionally widest exactly where the premium is smallest.
- The wings are the illiquid legs. A 200-point-out NIFTY option on the current weekly is usually fine. The same distance on a thinner index, a monthly contract, or late on expiry day often is not, and a wing you cannot exit cleanly is a wing that did not do its job.
- Order-size limits apply per leg. The exchange's freeze quantity caps how large a single order can be, so a large butterfly becomes several orders per leg, with the fill risk that implies across four legs that are supposed to go on together.
- Legging in is a different position. If the four legs do not fill together, you were briefly holding something other than a butterfly. Our own slippage work consistently shows that the gap between a modelled multi-leg fill and a real one is where backtest results go to die.
Against a ₹125 credit with a ₹75 maximum loss, a few rupees per leg of slippage is not a rounding error — it is a meaningful share of the entire payoff. This is the main reason our desk does not run butterflies as a default structure.
Managing it once it is open
The maximum profit on an iron butterfly needs the index to close exactly on the middle strike. That almost never happens, so planning to collect the full credit is planning for something rare. The realistic plan is to collect part of it and leave.
- Take part of the profit early. Once a good share of the credit has decayed, closing removes the risk of the last-hour move. Our own logged sessions show how much can be given back late: the median give-back from the intraday peak to the close was 42.8%.
- Use a clock exit. Decide a time after which you no longer hold, because gamma is highest in the last stretch. Our notes on square-off on expiry day and the expiry-day premium clock show how the premium actually decays through the session.
- Use a loss stop on the whole position. The wing makes the worst case known, not acceptable. Write down the loss at which you leave, well before the wing. See trailing stop-loss for short options.
- Be careful with adjustments. Rolling a challenged side toward spot, or inverting the shorts so the call sits below the put, can bring in extra credit and widen the breakeven. It also adds legs, spreads and a more complicated position under pressure. Option Alpha's guide shows the mechanics of inverting in detail; we mostly prefer a clean exit to a repaired trade.
Settlement: what is different in India
Most English-language guides spend a paragraph on early assignment, where a short leg is exercised against you before expiry. NIFTY and SENSEX options are European-style and cash-settled, so they cannot be exercised early and nothing is delivered. At expiry the in-the-money leg is simply settled in rupees. Stock options are different, since they settle by physical delivery, which can leave you with shares and a margin call if you hold an in-the-money leg into expiry. The short iron butterfly page from the Options Industry Council covers the US-style assignment and expiration risks if you want the contrast.
The reverse trade: long iron butterfly
Flip every leg and you have a long iron butterfly: you buy the at-the-money straddle and sell the wings, paying a debit, and you profit if the index moves beyond the break-evens. It is a way to bet on a large move with a capped cost, and some guides show it for markets expected to break out of the range. It is the opposite of what a premium seller is doing, and the same four-leg cost drag applies, so we mention it only so you do not confuse it with the short version when you see "iron butterfly" on a chain.
When it makes sense, and when it does not
The usual advice is to sell an iron butterfly when you expect a quiet, range-bound market and when implied volatility is elevated and likely to fall, for example before a known event. That is a fair description of when the structure can work. What the advice leaves out is the cost of being wrong in either direction. If the event produces the move that justified the high implied volatility, the narrow tent is the first thing to lose. If volatility stays high, the vega leg hurts as well. For how implied volatility is built and read, see implied volatility explained and how we budget premium against India VIX.
Where this fits in our own process
Honestly: it mostly does not. Our expiry-day baskets are built on naked or lightly-hedged strangle and straddle structures, sized to the account, with defined-risk conversion kept as a deliberate exception for known event windows rather than the base case — the reasoning and two logged examples are in our piece on vertical spreads and when we cap risk instead of selling naked.
If you want to evaluate a butterfly properly rather than take anyone's word for it, the test is specific and you can run it: take the structure's full four-leg cost, apply realistic slippage per leg, and score it over a sample that includes low-volatility, high-volatility and trending regimes rather than a handful of recent quiet expiries. That is the workflow our guide to options backtesting software in India is about, and it is the only thing that settles a structure question. A payoff diagram is a drawing. A regime-split backtest with honest costs is evidence.
To see the shape without risking anything, build the four legs in a free payoff tool and move the index around. Our comparison of payoff chart builders in India lists what each does, and how to read a payoff diagram without a builder shows how to check one by hand. Do the arithmetic yourself once, the way we did above, and you will catch most wrong numbers in other people's articles.
Before any of that, the strike-selection layer underneath all of it matters more than the structure choice: see ITM, OTM and ATM as the filter that decides your strike, and NIFTY lot size and position sizing for how a known maximum loss should change your lot count rather than just reassure you.
Frequently Asked Questions
What is a butterfly strategy in options trading?
A butterfly is a four-leg position across three equally spaced strikes whose payoff is a tent peaked at the middle strike. A long call butterfly buys one lower-strike call, sells two middle-strike calls and buys one higher-strike call for a net debit. An iron butterfly sells an at-the-money call and put and buys an out-of-the-money call and put equidistant on either side, for a net credit. Both want the underlying to finish near the middle strike; both have a fixed maximum loss.
What is the difference between a butterfly and an iron butterfly?
The payoff shape is effectively the same tent, but the cash flow is opposite. A long call butterfly is built from calls only and is entered for a net debit, so you pay to put it on. An iron butterfly is built from both a call spread and a put spread around the same middle strike and is entered for a net credit, so you collect premium. Premium sellers almost always mean the iron butterfly.
Is an iron butterfly just a short straddle with protection?
Yes, that is the most useful way to read it. Remove the two long wing options and what remains is an at-the-money short straddle. The wings cap the maximum loss at the wing width minus the net credit, in exchange for a smaller credit and a narrower breakeven range. They barely change gamma exposure near expiry, because the short legs still sit at the money and the bought wings are too far out to offset them until the index is already close to a wing.
How is maximum profit and maximum loss calculated on an iron butterfly?
Maximum profit is the net credit received, realised only if the underlying expires exactly at the middle strike. Maximum loss is the wing width minus the net credit. Breakevens are the middle strike plus and minus the net credit. For example, with 200-point wings and a net credit of 125, maximum profit is 125 per unit, maximum loss is 75 per unit, and the breakevens sit 125 points either side of the middle strike.
Is an iron butterfly better than an iron condor?
Neither is better; they price different bets. An iron butterfly shorts both legs at the same at-the-money strike, so it collects more credit but needs the underlying to finish near that one strike. An iron condor shorts two separated out-of-the-money strikes, so it collects less but has a wide flat profit zone between them. The butterfly is the more aggressive structure and depends on a pin; the condor depends only on staying inside a range.
Does EliteAlgo trade butterfly spreads?
No, not as a default structure. Our expiry-day baskets are built on naked or lightly-hedged strangle and straddle structures sized to the account, with defined-risk conversion used as a deliberate exception around known event windows. In our own signal-driven testing across 438 trading days, the defined-risk iron condor variant lost more than the naked short strangle, and none of eighteen structure-and-parameter combinations passed our acceptance gate.
Why are butterfly spreads expensive to trade in practice?
Because there are four legs. You cross a bid-ask spread on each one entering and again exiting, and the two wing legs are the furthest out of the money, so they are the thinnest and carry proportionally the widest spreads relative to their premium. Exchange freeze-quantity limits also split a large position into multiple orders per leg, adding fill risk. Against a small net credit, that cumulative slippage is a material share of the whole payoff, not a rounding error.
Is an iron butterfly bullish or bearish?
Neither. It is a neutral position that wants the index to finish close to the middle strike. If you set the middle strike above or below the current spot, you add a mild directional lean, but the standard version is struck at the money. A strong move in either direction, past a wing, is what takes it to maximum loss.
Can an iron butterfly be adjusted once it is open?
Yes, but every adjustment adds legs, and every leg adds slippage. The usual moves are rolling the untouched side toward spot, widening the wings, or closing one spread. We would rather use a pre-set exit: a stop on total loss, a time exit before the final hour, or taking part of the profit early. Adjusting a position that is already moving against you usually means paying more spreads to hold a worse trade.
Is there early assignment risk on NIFTY iron butterflies?
No. NIFTY and SENSEX index options are European-style and cash-settled, so a short leg cannot be exercised early and nothing is delivered. Many US guides warn about early assignment; that warning does not apply to index options here. It does apply, in a different form, to stock options, which settle by physical delivery if they are in the money at expiry.
The Bottom Line
A butterfly is a precise instrument: it pays well if the index finishes near one strike and it fixes your loss if it does not. The iron butterfly is the version a premium seller will actually be offered, and it is a short straddle with the tail cut off at a price of roughly a third of the credit and a third of the breakeven range. Those are fair terms if the structure inside the wings has an edge. Our own tests on signal-driven option selling found the defined-risk variant losing more than the naked one and no combination clearing our gate, so we do not run butterflies as a default and we would not tell you to. Price the four-leg slippage, test it across regimes on your own data, and treat a known maximum loss as a number to decide about rather than a reason to relax.
If you take one habit from this page, make it the straddle check: compare the iron butterfly's credit with the price of the at-the-money straddle before you enter, because that single comparison shows how much of the market's expected move your breakevens are asking the index to stay inside.
This article is for educational and informational purposes only and does not constitute investment advice. EliteAlgo is proprietary trading research and analytical software; it is not a SEBI-registered investment adviser and does not provide investment advice or trading tips. Options trading, including butterflies, iron butterflies, naked straddles and naked strangles, involves substantial risk of loss and is not suitable for all investors. Backtested and logged results describe what our own data did over a specific sample and do not guarantee future outcomes or imply any expected return. Paper trade any structure discussed here before deploying live capital, verify current contract specifications and margins with NSE and your broker, and consult a SEBI-registered investment advisor before trading derivatives.