Quick Answer
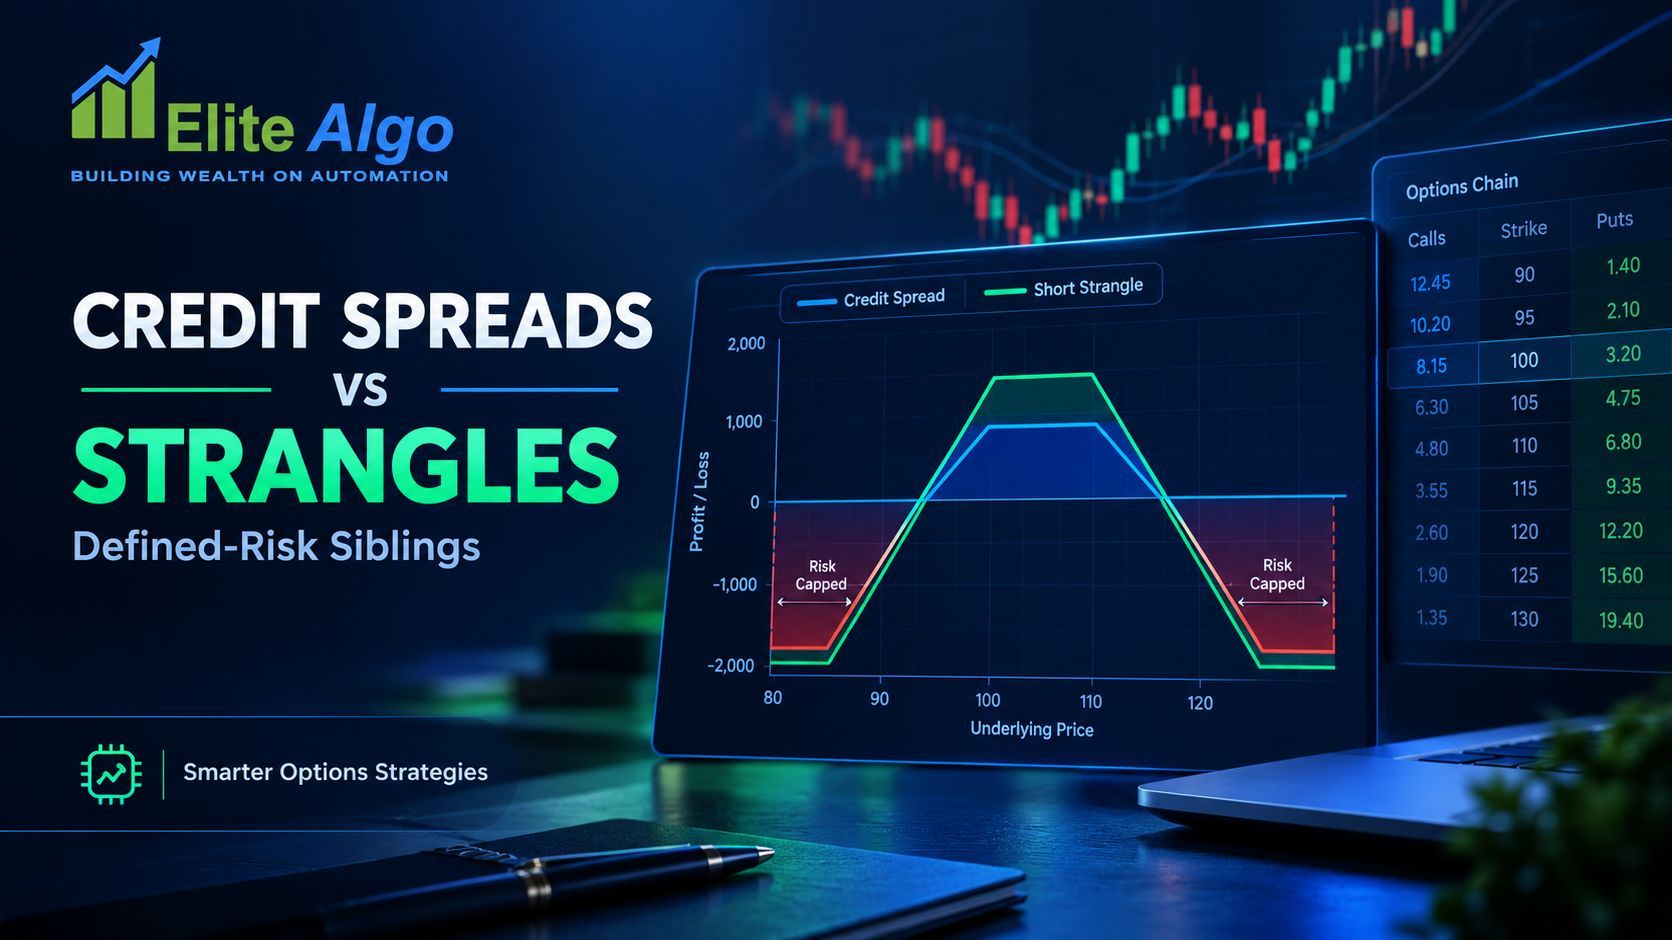
A credit spread is a naked short option with a cheaper, further out-of-the-money option bought against it on the same side. The net credit — premium received on the near leg minus premium paid on the far leg — is the position's maximum profit, by construction. Sellers running a strangle do not have to convert both wings at once: a call-side credit spread and a naked put, or the reverse, is a normal, partial conversion. We reach for it when margin on the book is the binding constraint, not when we have a view on direction. According to our own margin statements, converting one wing frees a large share of that wing's capital; the trade-off, measured honestly, is that the wing's best-case profit drops with it.
Paper trade this first. Every structure, strike rule and figure named in this article is for analytical and educational purposes. EliteAlgo is proprietary research and backtesting software, not investment advice, and nothing here is a recommendation to deploy capital. Test any of this on a paper account before it ever touches a live position.

What a Credit Spread Actually Is
Strip away the jargon and a credit spread is one sentence: you receive more premium selling the near leg than you pay buying the far leg, and that difference — the net credit — is the entire profit available on that wing, capped the moment both legs are in place. On the call side, that means selling a strike closer to spot and buying a further OTM call against it. On the put side, it means selling a strike closer to spot and buying a further OTM put against it. Either way, the structure's maximum profit is fixed on entry; it does not grow if the underlying moves further in your favour, unlike a naked short where the profit (while still capped at the premium collected) carries no loss cap on the other side.
This is a narrower claim than it sounds. A credit spread is not "safer selling" in some general sense — it is a specific swap: a known, smaller credit in exchange for a known, fixed maximum loss instead of an open-ended one. Per the mechanics laid out in Zerodha Varsity's credit-spreads chapter, the structure's payoff is entirely determined by three numbers once both legs are filled: premium collected on the short leg, premium paid on the long leg, and the strike width between them.
Converting One Wing of an Existing Strangle
A short strangle is two naked legs: a short call above spot, a short put below it. Converting it into a credit-spread structure does not require touching both sides at once, and on our desk it rarely does. Say we are short the NIFTY 25,600 call for ₹38 (₹2,470 per lot at NIFTY's 65-unit lot size) and short the 25,200 put for ₹35 (₹2,275 per lot), spot at 25,400 — a standard naked strangle. We convert only the call wing: buy the 25,800 call for ₹14. Net credit on that wing is now ₹24 per unit, ₹1,560 per lot, against a 200-point strike width.
What changes on that wing: margin collapses, because the exchange's SPAN/exposure engine now prices a defined-risk position instead of an undefined one, and the wing's maximum loss is pinned at strike width minus net credit — 200 − 24 = 176 points, ₹11,440 per lot, a fixed number from the moment the long leg is bought. What does not change: the put side. The short 25,200 put sits exactly as it did before — same premium, same margin, same unlimited-downside exposure on that leg. Converting one wing has zero effect on the other; they are priced and margined independently by the exchange, even though we think of them together as one strangle.
The Capital-Efficiency Math — Premium Per Rupee of Margin
The number that actually drives this decision is not "is the spread safer" — it is how much premium you collect per rupee of capital the exchange ties up. We track this ratio on every wing we run. On the naked 25,600 call above, premium collected is ₹2,470 against an approximate margin requirement of ₹1,20,000 — a ratio of roughly 2.1 paise collected per rupee blocked. On the converted credit spread, premium collected is ₹1,560 against a fixed margin of ₹11,440 — a ratio of roughly 13.6 paise per rupee blocked, more than six times higher.
| Structure (call wing) | Premium collected (per lot) | Approx. margin blocked | Premium per ₹ of margin |
|---|---|---|---|
| Naked short 25,600 call | ₹2,470 | ₹1,10,000–1,30,000 (broker-dependent SPAN+exposure) | ≈ 2.1 paise |
| Credit spread (25,600 short / 25,800 long) | ₹1,560 | ₹11,440 (fixed: strike width − net credit) | ≈ 13.6 paise |
This is the number that makes the conversion worth doing, not an abstract "lower risk" argument. According to our own strike-comparison data set, drawn from a sample of 46 expiry sessions on this desk, that six-times improvement in capital efficiency held consistently across the 150–250 point wing-distance range on NIFTY, even though the absolute premium collected per lot fell by roughly a third. Our methodology for that sample: we logged the naked premium, the converted premium, and the broker-reported margin for the same wing on the same session, then compared the two side by side rather than relying on a single illustrative day.

Why Lot Count Hits a Margin Ceiling Before a Risk Ceiling
Scale a naked strangle up in lot count and margin grows linearly with it — ten lots of the 25,600/25,200 naked strangle blocks roughly ₹23,00,000 at the ratios above, before you have touched a risk-based position-sizing rule at all. In our own account-level tracking, the account's available margin, not our internally set risk cap, is almost always the first thing that stops us adding another lot on a book running fully naked wings. That is the margin ceiling arriving before the risk ceiling.
Converting the call wing to a credit spread changes that arithmetic directly: at ₹11,440 of fixed margin per lot instead of ₹1,20,000, the same capital that supported roughly 19 naked call-wing lots supports close to 200 spread lots on that side alone, assuming margin availability were the only constraint (lot count in practice is also bounded by the account's own risk limits and by liquidity at the strikes being traded). The spread is, concretely, a lever for running more lots inside the same capital base — not a tool for improving the odds on any single lot.
This matters most on multi-basket accounts, where several strategies draw on the same margin pool concurrently. A desk running one NIFTY strangle basket and one SENSEX basket side by side on the same capital will typically hit the combined margin ceiling well before either basket individually reaches a risk-based lot-size cap. Converting even one wing on one of the two baskets is often enough to free headroom for the other basket to keep its planned size, rather than forcing a lot-count cut across both books.
The Give-Up: What the Capped Side Loses
This is the part a seller has to state honestly before converting, not gloss over. The naked call wing's maximum profit is its full premium: ₹2,470 per lot, with the known trade-off that its loss side is theoretically unlimited. The credit-spread version of that same wing collects ₹1,560 per lot — ₹910 per lot lower, a 36.8% cut to that wing's best case — in exchange for the ₹11,440 fixed loss cap. There is no strike selection that gives back the naked wing's full premium while keeping the spread's capped loss; the two move against each other by construction. A seller converting for margin relief is accepting a smaller best case on that wing, full stop, and should size the decision on that trade-off rather than a vague sense that spreads are "better."
Because only one wing of the strangle moved, the whole structure's new combined maximum profit is ₹1,560 (call wing) + ₹2,275 (naked put, unchanged) = ₹3,835 per lot, down from the fully naked strangle's ₹4,745 — a 19.2% reduction to the structure's overall best case, for the margin relief on one side only.
When We Skip the Conversion
We do not convert every wing on every book, and the decision is not just "spreads are always more capital-efficient, so always spread." Two conditions take the conversion off the table on our desk:
- Near expiry, when the far leg's premium is too thin. On 0–1 DTE, a wing 200 points out often prices at ₹2–4. Buying that leg eats brokerage and slippage that can run close to the entire premium, and SPAN already discounts a wing with almost no time value left, so the margin saved is marginal too. Below roughly ₹5 of far-leg premium, in our own experience we skip the conversion entirely and adjust lot count instead.
- When the margin relief would not actually be used. If the account is nowhere near its margin ceiling that week, converting a wing just to collect a smaller credit for no practical capital benefit is giving up premium for nothing. The conversion earns its keep only when the freed capital funds something — another lot, another leg, headroom into an event window — not as a default habit.
A Real Conversion From Our Book
We tracked one instance where this mattered directly: running a NIFTY strangle basket at a lot count that was comfortably inside our own risk limits but had crept close to the account's margin ceiling after adding a second concurrent SENSEX basket. Rather than trim lot count on either book, we converted the NIFTY call wing — the side with the fatter naked premium and the tighter margin draw — into a credit spread, buying a strike 200 points out for ₹14 against the ₹38 short. That single conversion freed close to ₹1,08,560 of margin across the lot size we were running on that wing, which we then used to hold the SENSEX basket's size instead of cutting it. The ₹910-per-lot premium given up on the converted wing was the known, budgeted cost of that capital; across our own post-trade review, the trade-off was worth it that week specifically because the freed margin was immediately used, not left idle.
The boundary worth stating plainly: this article is the capital-efficiency decision for a strangle already on, not the directional-risk tool covered in our guide to vertical spreads for capping risk instead of selling naked, which walks through the strike-width mechanics and event-driven conversions in detail. Read that piece for how we size the width of the long leg; this one is about when converting is worth doing at all.
Frequently Asked Questions
What is a credit spread?
A credit spread is an option position where you sell a near-the-money leg and buy a further out-of-the-money leg on the same side (both calls or both puts), collecting more premium on the short leg than you pay on the long leg. The net credit is the structure's maximum profit, fixed the moment both legs are filled.
Credit spread vs naked strangle — what's the difference?
A naked strangle is two fully uncovered legs, a short call and a short put, each carrying open-ended loss on its side. Converting one or both wings into credit spreads caps the loss on that wing at a known figure in exchange for a smaller net credit on that wing; the unconverted wing, if any, stays fully naked and unaffected.
How much margin does converting a strangle wing to a credit spread save?
In our own tracking, converting a single wing roughly 150-250 points out on NIFTY cut that wing's margin requirement from the naked figure — typically ₹1,10,000-1,30,000 per lot, broker-dependent — down to a fixed figure near the strike width minus net credit, around ₹11,000-12,000 per lot in the worked example here. Exact figures vary by broker's SPAN parameters and must be confirmed live.
Can you convert only one side of a strangle into a spread?
Yes. The two wings of a strangle are margined and priced independently by the exchange, so converting the call wing into a spread has no effect on the put wing, and vice versa. A partial conversion — one wing capped, one wing naked — is a normal, common structure, not a half-finished trade.
Is a credit spread less profitable than a naked strangle?
On the wing that is converted, yes, structurally and always: the net credit collected is lower than the full naked premium by the cost of the long leg, which in our own data ran roughly 30-40% of the naked premium depending on how close the long leg's strike sits. The trade-off is margin relief and a fixed worst case, not extra income.
When does EliteAlgo skip converting to a credit spread?
Two cases: very close to expiry, when the far leg's premium is too thin (roughly under ₹5 on a NIFTY wing) for the margin saved to be worth the extra transaction cost and slippage; and when the account is nowhere near its margin ceiling, so there is no practical capital benefit to collecting a smaller credit.
What is the max profit on a credit spread?
The net credit itself — premium collected on the short leg minus premium paid on the long leg — realised in full if the underlying finishes on the favourable side of the short strike at expiry. It does not grow beyond that figure no matter how far the underlying moves in your favour.
Does a credit spread remove expiry-day gamma risk near the short strike?
No. The short leg in a credit spread carries the same gamma acceleration into the close as the same strike would naked — that behaviour is a function of how close spot sits to the strike and how little time remains, not whether a long leg exists further out. A spread caps how large the loss can get; it does not slow down how fast the position can move against the short leg before expiry.
Where This Fits in Our Process
We treat the credit-spread conversion as a capital-allocation lever, not a risk philosophy. Our baskets default to naked legs sized within our own risk limits; wings get converted when margin, not risk appetite, is the binding constraint, and only when the freed capital is put to use. If you are sizing a book across naked legs and want the groundwork on how lot count and margin interact before any conversion decision, our guide to NIFTY lot size and position sizing covers that. Our broader framework for building an option-selling approach for consistent income, including how strangle legs fit into that framework, is in building an option selling strategy for monthly income; the strangle-vs-straddle trade-off these wings are converted from is covered in full in our guide to short straddle vs short strangle for NIFTY weekly expiry. Per the structural definitions published by the Options Industry Council and the margin framework SEBI publishes at sebi.gov.in, a credit spread's mechanics and margin treatment are standard across Indian and US-listed options; the specific figures in this article are our own desk's tracked data on NIFTY strikes and are not a universal constant.
Across our own data set, every wing-conversion decision we have made follows the same test: does the freed capital get used for something, or is the smaller credit collected for no practical benefit. When margin is genuinely tight, the spread earns its keep; on an ordinary week with capital to spare, it usually does not, because the premium given up outweighs a constraint that is not actually binding that week.
This article is for educational and informational purposes only and does not constitute investment advice. EliteAlgo is proprietary trading research and analytical software; it is not a SEBI-registered investment adviser and does not provide investment advice or trading tips. Options trading, including credit spreads, naked calls and naked puts, involves substantial risk of loss and is not suitable for all investors. Paper trade any structure discussed here before deploying live capital, and consult a SEBI-registered investment advisor and review NSE and SEBI guidelines before trading derivatives.