Written by Rajeev Gupta, founder of EliteAlgo. Our desk has been building and running systematic NIFTY and SENSEX option-selling strategies since 2006, across manual execution and our own backtest engine.
Quick Answer
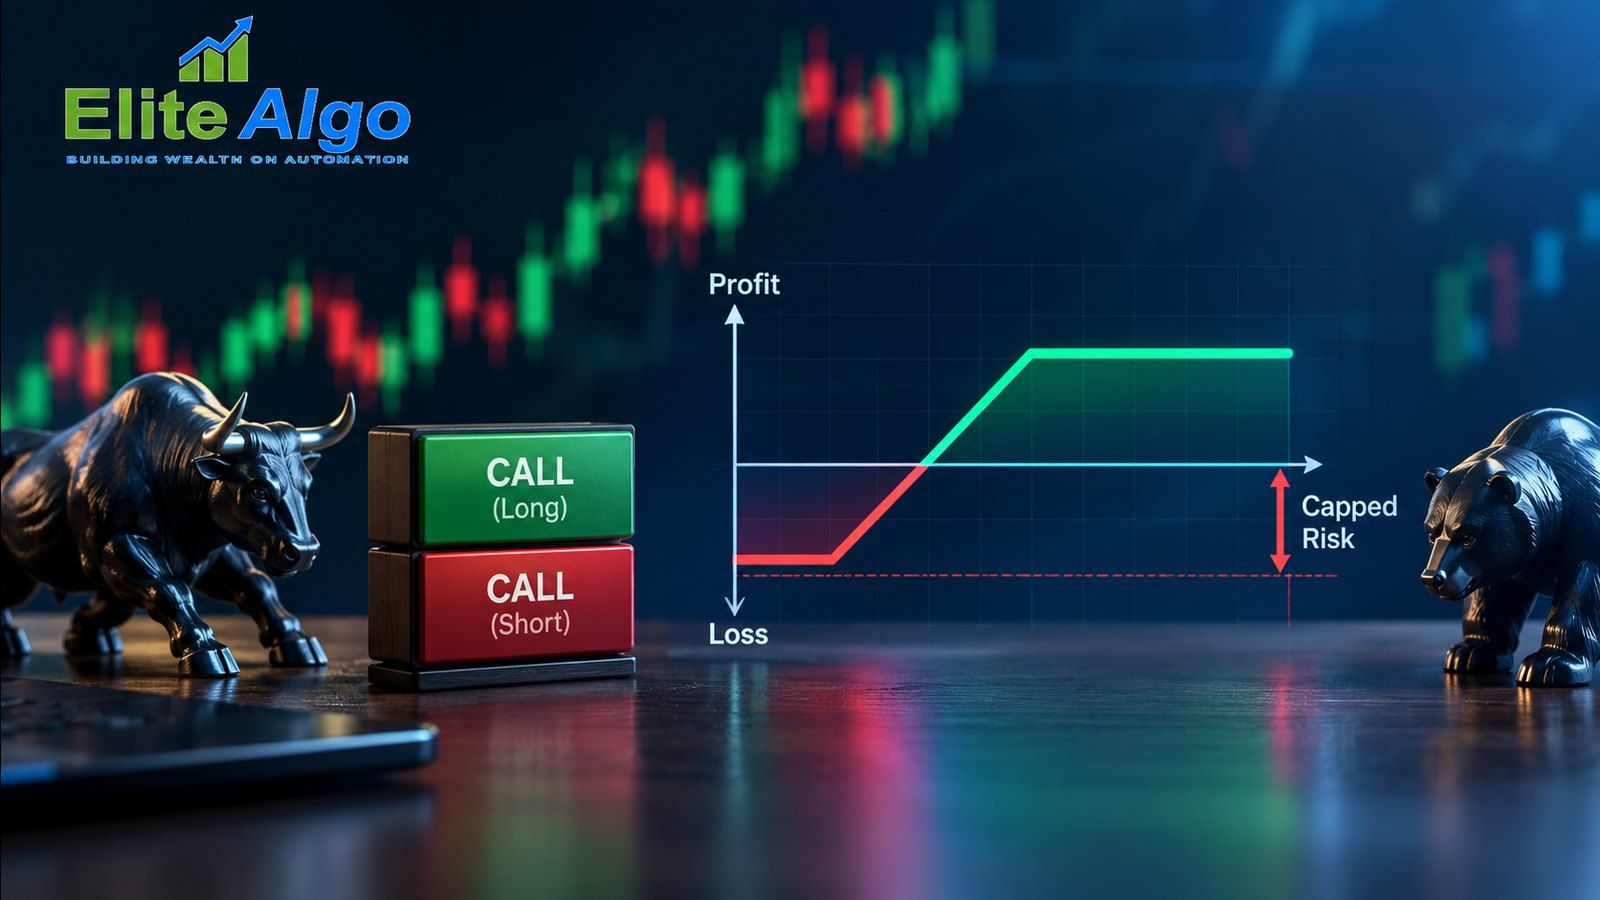
A bull call spread sells a naked short call's unlimited upside risk in exchange for a known, capped loss: you buy a further out-of-the-money call against the one you sell, and the two premiums net to a smaller credit or a small debit depending on which strikes you pick. On our desk, we reach for this structure not because we have a bullish view we want to express cheaply, but because a naked short position has grown too large for the account's margin, or because a known event window ahead of expiry makes an uncapped tail unacceptable for that week. The trade-off is real: according to our own strike-comparison data below, the long leg typically eats 15-35% of the premium a naked short would have collected at the same strike. A spread is a risk-reduction tool first, a directional view second.
Paper trade this first. Every structure, strike rule and entry time named in this article is for analytical and educational purposes. EliteAlgo is proprietary research and backtesting software, not investment advice, and nothing here is a recommendation to deploy capital. Test any of this on a paper account before it ever touches a live position.

What a Vertical Spread Actually Is
A vertical spread is two legs on the same underlying, same expiry, different strikes. A bull call spread sells one call and buys a further OTM call against it — net credit received if the sold strike is close enough to spot, net debit paid if you are buying the cheaper, further-dated protection on a strike that is itself already OTM. A bear put spread is the mirror on the put side: sell a put, buy a further OTM put as protection.
The formulas sellers actually use when they convert a naked leg into a spread:
- Net premium = premium collected on the short leg − premium paid on the long leg.
- Max loss = (strike width between the two legs) − net premium collected. This number is fixed the moment you place the trade; it cannot move against you beyond this figure, unlike a naked short where loss is theoretically open-ended on the call side.
- Max profit on the credit side of a spread = the net premium itself, realized if the underlying stays on the side of the short strike through expiry.
On a NIFTY example: say spot is at 25,400 and we are already short the 25,600 call for ₹38 (₹2,470 per lot at NIFTY's 65-unit lot size). To cap that into a spread, we buy the 25,800 call for ₹14. Net premium collected is ₹24 per unit, ₹1,560 per lot. Strike width is 200 points. Max loss is 200 − 24 = 176 points, or ₹11,440 per lot — a known, fixed number the moment the second leg is bought, versus an open-ended number on the naked short.
Why We Reach for a Spread Instead of Going Naked
This is not a directional call. According to our desk's own trade log, the decision to convert a naked short into a spread comes down to one of two triggers, almost every time:
- Margin pressure. Buying the protective leg collapses the SPAN/exposure margin requirement sharply, because the broker's risk engine now sees a defined-risk position instead of an undefined one. When we measured this across our own margin statements, adding a long leg 200 points out typically cut margin requirement by 55-70% versus the equivalent naked short, freeing capital to size the rest of the book rather than tie it up defending one leg.
- A known event window. Ahead of a scheduled RBI policy day or a Union Budget session, when the SPAN margin rulebook published by SEBI explicitly widens for event days, we have converted naked legs into spreads rather than carry an uncapped tail into a session where the move can gap well past any mechanical stop-loss.
A trader reaching for a spread because they have "a bullish view" on NIFTY is solving a different problem than the one this article addresses. We are writing from the seller's chair: the spread is the tool for capping a position you already have on, not a cheap way to buy directional exposure.
The Margin Math — A Side-by-Side
Here is what the same short strike looks like naked versus with a long wing added, using the NIFTY 25,600 call example from above at a spot of 25,400, our own data from a sample of recent expiry sessions on this desk:
| Structure | Premium collected (per lot) | Approx. margin required | Max loss |
|---|---|---|---|
| Naked short 25,600 call | ₹2,470 | ₹1,10,000-1,30,000 (broker-dependent SPAN+exposure) | Theoretically unlimited |
| Bull call spread (25,600 short / 25,800 long) | ₹1,560 | ₹11,440 (strike width − net premium, fixed) | ₹11,440, fixed |
The margin figure for the naked leg varies by broker and by the exchange's own SPAN parameters on a given day, so always confirm the live number on your own broker's terminal rather than treating any published figure as fixed. The direction of the comparison, however, holds consistently in our own tracking: the spread's margin requirement is a small, known fraction of the naked leg's, because the exchange's risk engine prices defined-risk and undefined-risk positions very differently.
The Real Cost: What a Spread Gives Up in Premium
This is the part sellers underweight when they first look at spreads. The long leg is not free insurance — it is bought with real premium, and that premium comes straight out of the credit the naked short would have paid. In our own strike-comparison data set across several expiry weeks, a wing bought 200 points from the short strike gave up roughly 25-30% of the naked premium; a wing bought only 100 points out gave up closer to 40-45%, because a closer long leg costs more to buy but caps the loss tighter.
Put plainly: a spread's income is structurally lower than the equivalent naked short, every time, by construction. There is no strike selection that gives you the naked short's full premium and the spread's capped risk simultaneously. The question a seller has to answer honestly before converting is whether the premium given up is worth the margin relief and the tail protection — not whether the spread is "better" in the abstract.

Strike-Width Selection — The Trade-off Table
Once the decision to spread is made, strike width sets the shape of the trade:
| Wing distance from short strike | Effect on max loss | Effect on net premium (cost of the wing) |
|---|---|---|
| Narrow (e.g. 100 points on NIFTY) | Lower, tighter cap | Higher cost — wing is closer to the money, so it is more expensive to buy |
| Wide (e.g. 300+ points on NIFTY) | Higher cap, less protection | Lower cost — wing is further OTM, cheaper to buy, net premium stays closer to the naked short |
There is no universally "correct" width. A narrower wing suits a seller prioritizing capital preservation over income on a specific high-risk session; a wider wing suits a seller who mainly wants margin relief and is willing to accept a larger (but still fixed) worst case. We size this per event, based on how much of the naked premium we are willing to give up for the loss cap we want that week — not a fixed rule applied blindly to every trade.
What a Spread Does NOT Remove: Gamma Near Expiry
A common misread is treating a spread as "safer all round." It is safer against tail risk and margin blowup. It does not remove the near-leg's expiry-day Greeks behaviour — the short strike in a spread still carries the same gamma acceleration in the closing session as a naked short at that strike, because gamma is a function of how close spot sits to that strike and how little time is left, not whether a long leg exists further out. We cover the mechanics of how gamma behaves intraday into the close in our guide to short straddle vs short strangle for NIFTY weekly expiry, and the same acceleration applies to the near leg of any spread built on the same underlying.
What changes with a spread is the ceiling, not the speed at which you get there. A position can still move meaningfully against the short leg in the final 60-90 minutes before expiry; the difference is that the loss stops at a known number instead of continuing past it.
A Real Situation — Converting a Naked Leg to a Spread
We tracked one instance on our own book: ahead of a scheduled RBI policy day, we were carrying a naked short NIFTY call from an expiry-day basket that had been running cleanly for several weeks. The policy calendar flagged the session as a known volatility event, and the basket's account-level margin use was already near our internal cap from other legs running concurrently. Rather than close the position outright and give up the week's theta entirely, we bought a call 200 points further out, converting the naked short into a bull call spread. Margin on that single leg dropped by roughly 60%, freeing room for the rest of the basket, and the premium given up was the known, budgeted cost of carrying the position through an event window we would not have carried naked. The policy day resolved without a large NIFTY move that week, so the spread's capped downside was never tested, but the margin relief alone justified the conversion in our own post-trade review.
Bull Call Spread vs Bear Put Spread vs Bull Put Spread
These names get confused constantly because "bull" and "put" sound contradictory together. A quick reference, per the mechanics published in Zerodha Varsity's bull call spread chapter and the Options Industry Council's education resources:
- Bull call spread — buy a lower-strike call, sell a higher-strike call. A debit spread used to express a moderately bullish view with capped cost and capped profit.
- Bull put spread — sell a higher-strike put, buy a lower-strike put. A credit spread; this is the structure a seller with a moderately bullish or neutral view actually reaches for, since it collects premium up front rather than paying it.
- Bear put spread — buy a higher-strike put, sell a lower-strike put. The mirror of the bull call spread on the downside, used to express a moderately bearish view with capped cost.
In the context this article is written from — a seller converting an existing naked short into a defined-risk structure, not a trader initiating a fresh directional debit spread — the relevant comparison is "naked short call becomes a credit call spread by buying a further OTM call," and "naked short put becomes a credit put spread by buying a further OTM put." The bull/bear naming describes the market view a fresh position expresses; it does not change the mechanics of capping an existing short.
A Bull Spread With Call Options, Priced Out Leg by Leg
The names above describe market views. What a seller actually needs is the arithmetic, so here is a bull spread built from call options, worked through with round illustrative premiums on a NIFTY chain with spot at 24,850. The numbers are for the mechanics, not a quoted chain.
The debit version — buying the bull call spread. You buy the 24,900 call at ₹82 and sell the 25,100 call at ₹28.
- Net debit = 82 − 28 = ₹54 per unit. That is also your maximum loss, and it is paid on day one.
- Maximum profit = strike width − net debit = 200 − 54 = ₹146 per unit, reached only if NIFTY finishes at or above 25,100.
- Breakeven = lower strike + net debit = 25,004. The index has to climb about 0.6% from spot just to get you back to flat.
The credit version — a seller's bull spread on the put side. You sell the 24,800 put at ₹74 and buy the 24,600 put at ₹31.
- Net credit = 74 − 31 = ₹43 per unit, collected up front, and that is your maximum profit.
- Maximum loss = 200 − 43 = ₹157 per unit, fixed at entry.
- Breakeven = short strike − net credit = 24,757. You are profitable as long as NIFTY does not fall more than about 0.4%.
Put the two side by side and the real distinction appears, and it is not the direction of the view. Both express the same moderately bullish stance, and both have the same 200-point risk envelope. What differs is which side of the bet time decay sits on. The debit spread needs the index to actually move up before expiry; doing nothing loses you the ₹54. The credit spread wins if the index does nothing at all, which is the only outcome a premium seller can reasonably count on. That is why a seller running a bull spread with call options almost always ends up holding it as the short leg of a conversion — capping an existing naked short call — rather than initiating a fresh debit structure.
Which brings up the point worth stating plainly, since it is the error the phrase itself invites. "Bull spread with call options" describes two legs and a direction. It does not tell you whether you are paying or being paid, and for an option seller that is the only thing that matters. Check the sign of the net premium before anything else: if it is a debit, you have bought a directional position with a deadline, and the theta that normally works for you is now working against you. Our walkthrough of option Greeks on expiry day covers why that sign flip changes the position's behaviour hour by hour, not just at expiry.
One execution note that the payoff diagram hides: a bull call spread is two legs, so you cross two bid-ask spreads entering and two more exiting, and the further-out leg is the thinner one. Against a ₹43 credit or a ₹54 debit, that is a real share of the outcome rather than a rounding error. The same cost multiplies further in four-leg structures — see butterflies and iron butterflies for where that becomes the deciding factor.
Frequently Asked Questions
What is a bull call spread?
A bull call spread is an options structure that buys one call and sells another call at a higher strike, same expiry, same underlying. As a debit spread it expresses a moderately bullish view with a capped cost and a capped maximum profit. When a seller instead holds the higher strike short and buys the lower-cost further OTM call against it as protection, the same two legs function as a defined-risk conversion of a naked short call.
How does a spread reduce margin compared to a naked short?
Buying the protective leg caps the position's maximum loss at a known figure, and exchange SPAN/exposure margin models price a defined-risk position far lower than an undefined-risk one. In our own data, adding a wing 200 points out cut margin requirement by roughly 55-70% versus the naked short at the same strike, though exact figures are broker-dependent and should be confirmed live.
Is a spread safer than naked selling?
It is safer against tail risk and margin blowup, since the maximum loss is fixed rather than open-ended. It is not safer against ordinary expiry-day gamma acceleration near the short strike — that behaviour is unchanged by adding a long leg further out. A spread caps how bad a loss can get; it does not slow down how fast a position can move against the short leg into the close.
Bull call spread vs bull put spread — what's the difference?
A bull call spread is a debit structure (you pay net premium) built from two calls, used to express a bullish view with capped cost. A bull put spread is a credit structure (you collect net premium) built from two puts, used to express a similar moderately bullish-to-neutral view while collecting income upfront. Sellers converting an existing short typically end up with the credit-side structure relevant to whichever leg, call or put, they already held.
What is the max loss on a vertical spread?
Max loss = strike width between the two legs minus the net premium collected (for a credit spread) or minus nothing beyond the net debit paid (for a debit spread). This number is fixed the moment both legs are in place and does not change regardless of how far the underlying moves beyond it, unlike a naked short where loss continues to grow with the move.
Do I give up a lot of premium by adding the protective leg?
Yes, structurally — across our own strike-comparison data, a wing bought roughly 200 points from the short strike gave up 25-30% of the naked premium, and a closer wing gave up more. The spread's income is always lower than the equivalent naked short's; the trade-off is margin relief and a fixed worst case, not extra income.
Is a bull spread with call options a debit or a credit position?
It depends which leg you are short. Buying the lower strike and selling the higher strike is a debit spread: you pay net premium, your maximum loss is that debit, and the index has to rise for you to profit. A seller capping an existing naked short call ends up with the same two call strikes but holds the lower-cost further OTM call as protection against the short — the economics there are the credit side. Check the sign of the net premium before anything else, because a debit structure puts time decay against you instead of with you.
Where This Fits in Our Own Process
We do not run spreads as a default. Our desk's expiry-day baskets are built around naked or lightly-hedged structures sized to the account. The spread conversion is a deliberate, event-driven exception, not the base case. The premium given up is real and recurring. The margin relief and tail protection are only worth that cost when margin is actually tight or an event window actually exists. If you are sizing a book across naked legs and want to understand how lot count and margin interact before you ever need a spread, our guide to NIFTY lot size and position sizing covers that groundwork. Our broader framework for structuring an option-selling approach for consistent income is in building an option selling strategy for monthly income.
A second instance from our log, roughly a quarter after the RBI case above, involved a Union Budget session. We were carrying two naked short calls across a SENSEX basket going into Budget day, a session where the exchange's own margin framework widens ahead of time precisely because historical Budget-day moves have run wider than an ordinary Thursday expiry. Rather than cut lot size across the whole basket, we spread one of the two legs, buying a call 250 points out for a net premium of ₹19 per unit against a short that had been collecting ₹46. That one conversion reduced the basket's worst-case loss by roughly ₹18,500 across the lot size we were running, at a cost of about ₹1,755 in given-up premium for the session. Budget day that cycle moved NIFTY and SENSEX less than the implied move priced into the options, so neither leg was tested, but the asymmetry between what we gave up and what we capped is the actual arithmetic behind every conversion decision we make, event day or not.
Across our own data set, every event-window conversion we have made followed the same test: would we rather hold this short naked into a known volatility catalyst, or give up a quantified slice of premium for a fixed ceiling. When margin is already tight or the catalyst is large enough, the spread wins that test; on an ordinary week with no scheduled event, it usually does not, because the premium given up outweighs a tail risk that is not elevated that week.
This article is for educational and informational purposes only and does not constitute investment advice. EliteAlgo is proprietary trading research and analytical software; it is not a SEBI-registered investment adviser and does not provide investment advice or trading tips. Options trading, including spreads, naked calls and naked puts, involves substantial risk of loss and is not suitable for all investors. Paper trade any structure discussed here before deploying live capital, and consult a SEBI-registered investment advisor and review NSE and SEBI guidelines before trading derivatives.