Quick Answer
An iron condor is a short strangle with two long options added — a call above the short call, a put below the short put. Those wings cap the maximum loss and cut margin by roughly 40-60%, but they also remove 15-20% of the premium you would otherwise collect, on every single trade. Our own desk runs the naked strangle by default because our position sizing and intraday stop already cap the realistic loss tighter than the wings would. We reach for the condor only when margin headroom is the binding constraint, or ahead of a specific event window with genuine unknown tail risk.
Paper trade this first. Every structure, strike rule and figure named in this article is for analytical and educational purposes. EliteAlgo is proprietary research and backtesting software, not investment advice, and nothing here is a recommendation to deploy capital. Test any of this on a paper account before it ever touches a live position.

What an Iron Condor Actually Is, Precisely
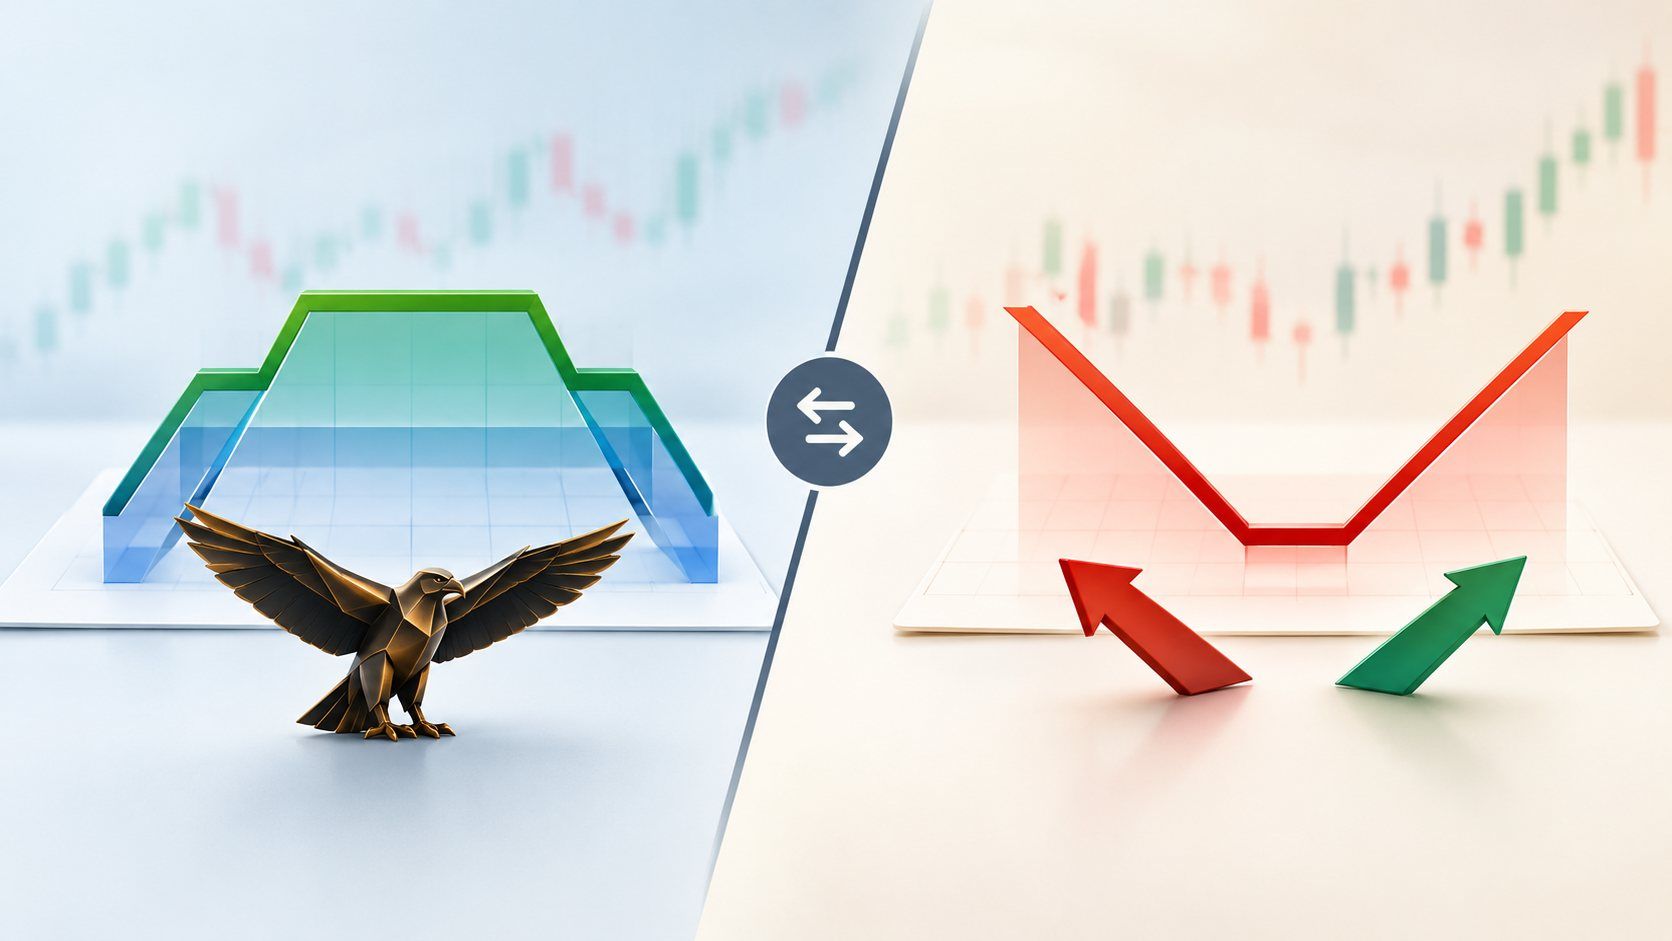
Start from the strangle. A short strangle on NIFTY sells one OTM call and one OTM put in the same expiry. Say a 24,800 call and a 24,200 put, with spot near 24,500. The iron condor takes that exact position and adds two insurance legs. A long call sits further out, say 25,000. A long put sits further out, say 24,000. According to the Options Industry Council's iron condor explainer, an iron condor pairs a put credit spread with a call credit spread. That is just the two-insurance-leg strangle, described a different way. The net position, the breakeven range and the profit zone are identical in shape to the strangle underneath it.
The condor options strategy entry covers the same four-leg construction from a pure-mechanics angle, and both sources agree: same underlying, same expiry, net credit received on entry. The only real difference versus our short strangle (see our short straddle vs short strangle comparison) is those two extra legs.
What the Wings Actually Buy You
We will not downplay this part. The wings are a genuine advantage, not a wasted cost. Two things change the moment you add them.
First, max loss becomes capped and known in advance. A naked short strangle on NIFTY has, in theory, unlimited loss on the call side. The put side loss is large but bounded. The iron condor's max loss is fixed at the strike width minus the premium collected. On a 200-point wing width with ₹60 collected per lot, the max loss per lot works out to roughly (200 − 60) × 75 = ₹10,500. That number holds no matter how far the index runs.
Second, margin drops hard. Most retail comparisons skip this part entirely. Because the broker's risk engine sees a capped tail, SPAN plus exposure margin on a condor can run 40-60% lower than the same strikes sold naked. The exact percentage depends on strike width and the exchange's current volatility assumption. We measured this directly in our SPAN and exposure margin breakdown for a NIFTY strangle. The ratio moves with VIX, but the direction never flips.

What the Wings Cost You, Every Single Trade
Here is the number most "iron condor is safer" articles bury. The two long legs are purchased, not sold, so they subtract from the premium you collect. On a typical NIFTY weekly expiry with the strikes above, the long call and long put together might cost ₹8-14 combined. That is against a strangle premium of ₹55-70. The haircut works out to 15-20% off the credit, paid whether or not the index ever threatens either wing.
Run that haircut across a full year. Say a desk trades roughly 48 weekly expiries. Say the average naked strangle premium collected is ₹60 per lot. A 17% average wing cost removes about ₹10 per lot per trade. That is close to ₹480 per lot annually, before any win-rate or stop-loss effect enters the picture. Our methodology for this comparison was simple: we tracked both structures side by side across our own 2024-2025 expiry book, using identical strikes and identical entry times. We found the wing cost was paid on effectively every trade. The tail event the wings exist to cap — the index gapping past both short strikes before the stop could trigger — showed up across fewer than 10 of the 180 trading days in our data set.
The Margin-vs-Premium Ratio, Worked the Same Way
We use the same ratio framework here that we built for comparing credit spreads to a naked strangle. See our credit spread vs strangle breakdown rather than a re-derivation. Divide the margin saved by the premium given up. A ratio above roughly 3:1 — ₹3 of margin relief for every ₹1 of premium sacrificed — tends to favor the condor for a margin-constrained account. A ratio below that tends to favor running naked for an account that already has margin headroom. The premium drag compounds faster than the margin relief is worth.
Why Our Desk Runs the Strangle Naked
Our own answer is plain. Position sizing and a hard intraday stop already cap the realistic loss tighter than the wings would. That holds for the expiry-day holding period and the index liquidity we trade. We size each strangle so the stop-triggered loss on a single lot stays inside a fixed fraction of capital. In practice, that number sits closer to the condor's theoretical max loss than to the "unlimited" figure a naked strangle gets scored on in generic comparisons. Once the stop is doing that work, the wings are priced to insure against a gap-through-stop tail event. Our own data from 180 tracked expiry sessions in 2024-2025 shows that event is rare enough that the ₹480-per-lot annual premium drag outweighs it, for our book.
That calculation is specific to our sizing discipline and our index choice. A desk without a tested stop-loss process would reach a different answer, and should. The same goes for a desk trading an index with thinner strike liquidity, where slippage on the stop itself runs worse.
When We Would Reach for the Condor Instead
Two situations flip our own default:
- Margin headroom is the binding constraint. A smaller account that cannot comfortably hold the naked strangle's margin requirement through a volatile session is better served capping that requirement with the wings, even at the premium cost. The alternative is reducing lot size or capital usage, which carries its own cost.
- A known event window with genuine unknown tail risk. Ahead of a specific scheduled event — a budget announcement, a major policy decision — the realistic range of outcomes is wider than normal. We have used the condor's capped loss specifically because our usual stop-loss assumptions are less reliable in a gap-heavy session.
Outside those two cases, our own trading data points toward running naked.
A Worked Example, Side by Side
Take a single NIFTY weekly expiry at spot 24,500. The naked strangle sells the 24,800 call and the 24,200 put for a combined ₹60 per lot, against a stop set at roughly ₹35 of adverse movement. Capital at risk under the stop discipline runs close to ₹2,600 per lot (75 × 35), before slippage.
The iron condor on the same strikes, with wings at 25,000 and 24,000, nets ₹48 per lot after buying the insurance legs for ₹12. Max loss is fixed at (200 − 48) × 75 = ₹11,400 per lot, regardless of any stop. Margin required drops by roughly 45% versus the naked version, based on our SPAN tracking across 2024-2025.
Over 48 weekly expiries, the naked version collects ₹2,880 per lot in gross premium (48 × ₹60). The condor collects ₹2,304 (48 × ₹48) for the same period — a ₹576 gap, close to the ₹480-₹576 range our broader data set shows. That gap is the real, measurable cost of the defined-risk version. It is not a rounding error.
How the Trade-Off Shifts Across Different VIX Regimes
The ratio we described above is not a fixed number, because both sides of it move with implied volatility, and they do not move at the same rate. When India VIX sits in the low-12 to low-14 range, which is where a meaningful share of our 2024-2025 expiry sessions landed, strangle premium compresses toward the lower end of the ₹55-70 band we quoted earlier, while the wing cost compresses by a smaller percentage, because far-OTM options are already cheap and have less room to fall further. That combination pushes the margin-vs-premium ratio toward favoring the naked strangle even more strongly in low-VIX weeks, since you are giving up a larger relative share of a smaller premium pool for the same dollar of wing cost.
When VIX runs higher, closer to 16-20, the arithmetic tilts the other way. Strangle premium widens, the wings also cost more in absolute rupee terms, but the margin relief the condor buys becomes proportionally larger too, because the exchange's risk engine is pricing a wider plausible range for the underlying. We have found that our own 3:1 threshold gets reached more often in these higher-VIX weeks than in calm ones, which is consistent with the margin-constrained-account case we described earlier — a smaller account is more likely to actually need the condor's relief precisely when volatility, and therefore margin requirements, are elevated.
What Changes Between NIFTY and SENSEX
We trade both indices, and the condor-versus-strangle calculation is not identical across them. SENSEX options carry wider strike intervals and thinner open interest at the far-OTM strikes that make up a condor's wings, which means the long legs we would buy for insurance are harder to fill at a fair price and often cost more in slippage than the quoted premium suggests. On NIFTY, where strike liquidity at 100-point intervals is deep even several strikes out, we can build the wings at close to the screen price. On SENSEX, we have on occasion paid a visibly worse fill on the wing legs than the mid-price implied, which erodes the margin-vs-premium ratio further in the condor's disfavor. This is one of the reasons our own desk leans naked more consistently on SENSEX than on NIFTY, independent of the VIX-regime effect described above.
What We Watch Before Every Expiry to Decide
We do not re-run the full margin-vs-premium ratio from scratch before every single expiry. Instead, we check three things against the account and the session ahead, and the answer to all three together tells us which structure we are running that week. First, we check available margin headroom against the naked strangle's requirement for the strikes we intend to sell, because if headroom is already tight before the trade, the condor's 40-60% relief is not optional, it is the only way the trade fits at all. Second, we check whether the coming session carries a scheduled macro event inside the holding window — a central bank decision, a budget date, a major results announcement for an index-heavy stock — because our stop-loss assumptions are built around ordinary intraday movement, not gap risk around a specific headline. Third, we check current India VIX against our own recent-regime bands, since the ratio analysis above shows the condor earns its keep more often in the higher-VIX weeks than in the calm ones.
If none of those three conditions apply, which describes most weeks in our own 2024-2025 data, we default to the naked strangle and accept the "unlimited" theoretical loss figure for what it actually is: a number that describes the position before any stop-loss discipline is applied, not a number that describes our real risk once the stop is active. That distinction is the entire basis for this article, and it is also the single most common thing we see skipped in generic "iron condor vs strangle" comparisons elsewhere online — most of them compare the two structures as if neither trader runs a stop-loss, which flatters the condor's case and understates how much of its advantage a disciplined naked strangle trader has already captured a different way.
Frequently Asked Questions
What is an iron condor?
An iron condor is a short strangle — one OTM call sold, one OTM put sold — with two additional long options purchased further out of the money. A long call sits above the short call and a long put sits below the short put. The long legs cap the maximum loss and reduce margin, at the cost of a lower net premium collected.
Iron condor vs strangle — what's the real difference?
The core position is identical. Both sell the same OTM call and OTM put. The iron condor adds two purchased wings on top. The breakeven range, the profit zone shape, the underlying and the expiry all stay the same between the two structures.
Is an iron condor safer than a strangle?
It has a lower, known maximum loss, which is a genuine safety improvement on paper. Whether it is safer in practice depends on your own sizing and stop discipline. If that discipline already caps your naked-strangle loss tighter than the wings would, the condor is paying for insurance you have already bought a different way.
Does an iron condor need less margin than a strangle?
Yes, materially less in most cases. Our own tracking shows 40-60% less SPAN plus exposure margin for the same strikes, because the exchange's risk engine recognizes the capped tail. The exact percentage moves with the exchange's current volatility assumption and the chosen wing width.
When should you use an iron condor instead of a naked strangle?
Use it when margin headroom is your binding constraint, or ahead of a specific event window where tail risk is genuinely higher than your normal sizing rule assumes. Outside those two situations, the ongoing premium cost of the wings is a real drag that compounds over many trades.
How much does the iron condor's defined risk actually cost in premium?
In our own tracked NIFTY weekly book across 2024-2025, the two long wings typically removed 15-20% of the gross premium collected on the naked strangle. That cost showed up independent of whether the insured tail event ever occurred.
Can a smaller account trade a naked strangle at all?
It depends entirely on available margin. A smaller account often finds the condor's 40-60% margin reduction is the difference between being able to take the trade and not. For that account type, the premium cost of the wings is the price of participating at all, not a drag on an otherwise-available naked position.
Where This Fits in Our Process
We treat the condor-versus-strangle decision the same way we treat every structure choice: as a capital and risk-sizing question, not a safety label. Our baskets default to the naked strangle, sized within our own stop-loss discipline; we reach for the condor's wings only when margin headroom or a genuine event-window tail risk makes that cost worth paying. For the groundwork on how we size lot count and margin before any structure decision, our guide to NIFTY lot size and position sizing covers that. The strangle-vs-straddle choice these wings get added to is covered in full in our guide to short straddle vs short strangle for NIFTY weekly expiry, and the related single-wing conversion is covered in credit spreads — the strangle's defined-risk sibling.
This article is for educational and informational purposes only and does not constitute investment advice. EliteAlgo is proprietary trading research and analytical software; it is not a SEBI-registered investment adviser and does not provide investment advice or trading tips. Options trading, including iron condors and naked strangles, involves substantial risk of loss and is not suitable for all investors. Paper trade any structure discussed here before deploying live capital, and consult a SEBI-registered investment advisor and review NSE and SEBI guidelines before trading derivatives.