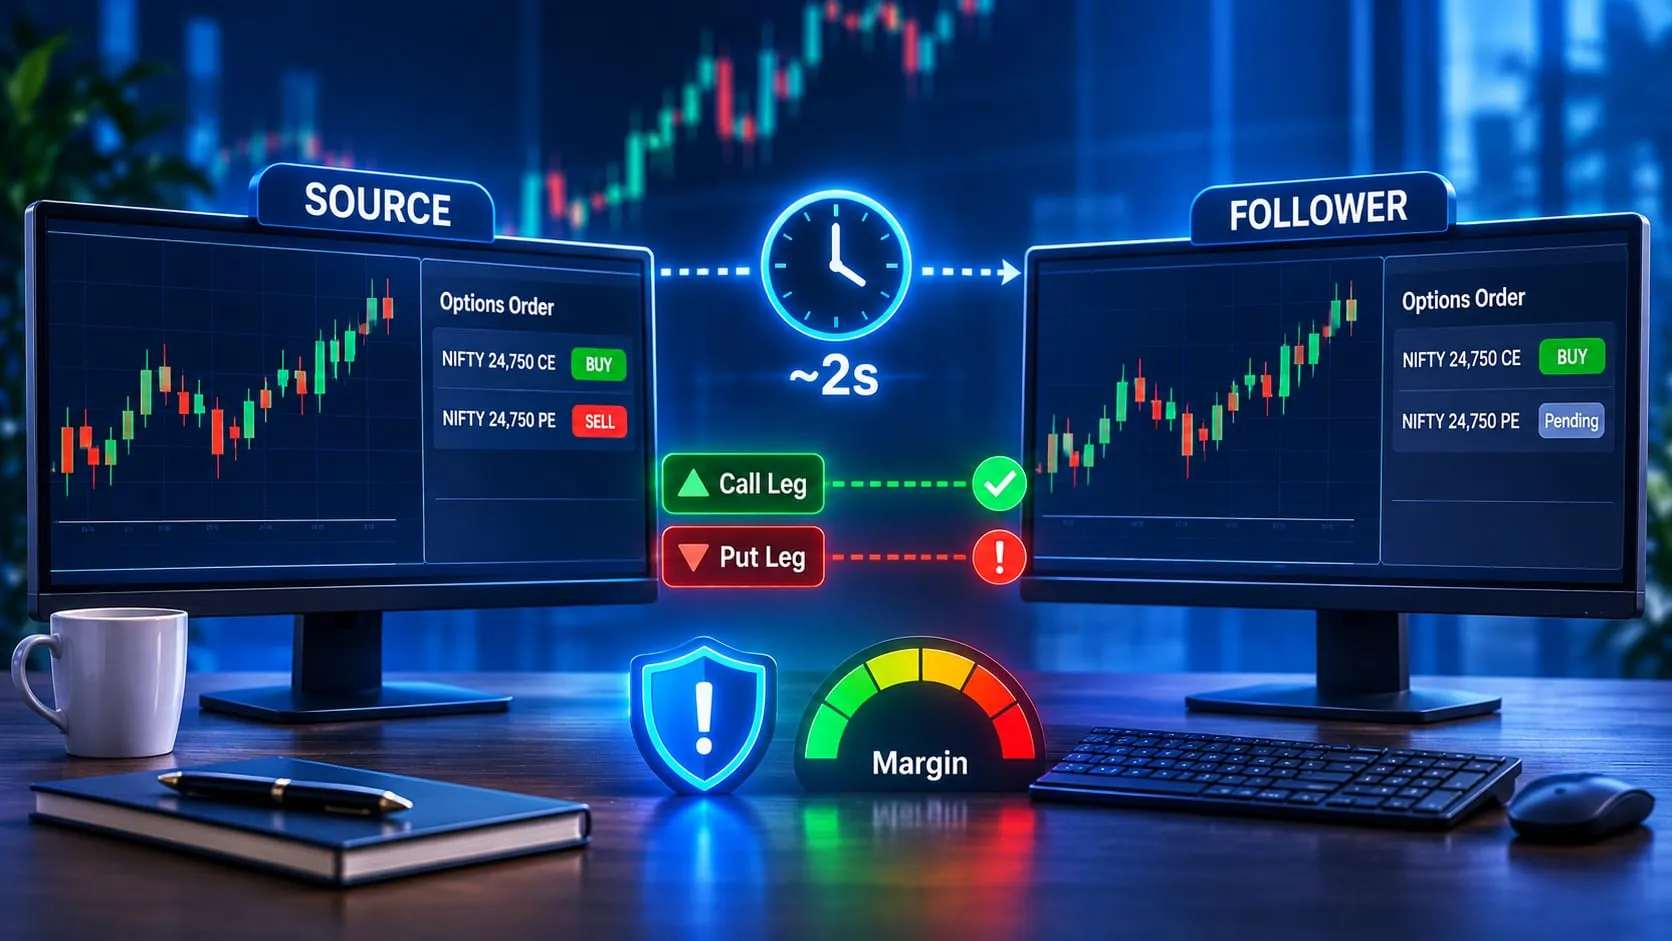
The pitch for copy trading fits in one sentence: pick a trader, link your broker account, and every position they take shows up in yours, scaled to your size. For equities that pitch mostly holds. For option selling it leaves out the parts that decide whether you make or lose money. A short strangle isn't a single price you can match. It's two legs, two strikes, one expiry and one entry moment, and the copy has to get all four right at once.
We trade NIFTY and SENSEX expiry-day option selling from our own desk, and our team built its own backtest engine to study fills, slippage and decay. This piece is about what breaks when somebody else's option-selling positions get mirrored into your account. We're not running a copy-trading service and we don't publish signals. We're writing it because readers keep asking whether copy trading would let them skip the learning curve, and the honest answer depends on mechanics most platform pages never mention.
Paper trade this first. Before you trust any copy-trading service with live capital, run it on paper and measure the copy latency itself: how closely each mirrored fill tracked the source account's fill, leg by leg. This article is EliteAlgo's own research, shared as analytical software and not as investment advice or a signal to act on.

What Copy Trading Actually Is, Mechanically
Strip away the marketing and a copy-trading setup has three moving parts. There's a source account where the lead trader (or an algo) places orders. There's a follower account that belongs to you. And there's a layer in between, usually broker API hooks, that watches the source for new orders and fires matching orders into the follower, scaled by a ratio you or the platform sets.
Scaling is the part people skim past. If the source trades 20 lots and your ratio is 1:10, your account is asked to trade 2 lots. If your capital is a tenth of theirs, that seems fair. It also quietly assumes your margin, your risk tolerance and your fill quality are a tenth of theirs too, and none of those scale linearly.
Latency is built in. The source order goes to the exchange, gets acknowledged, the hook sees the fill or the order event, the platform computes your size, then your broker receives and routes your order. Each hop takes time. Even a well-built pipeline adds a delay somewhere between a fraction of a second and a few seconds, and a retail-grade one can add much more when markets are busy. That delay is the root of nearly everything below.
What Copies Reasonably Well
Not everything breaks. The direction and structure of a trade copy fine when execution is quick and both accounts have similar margin headroom. If the source sells a 24,800 call and a 24,200 put on NIFTY weekly expiry, the follower will end up short the same two strikes in the same expiry. You can confirm that from the order book.
For slow, low-frequency trades, the timing gap barely matters. Someone who buys a stock and holds it for six months isn't hurt much if your copy fills two seconds late. Even there, the gap shows up in the cost basis, but it's rounding error against the holding period.
That's the case copy-trading marketing is built on, and it's a reasonable case. The trouble starts when the same machinery gets pointed at a product where timing and structure are the whole trade.
Where Option Selling Is Different
An equity copy trade is a single-instrument price match. If the source buys at ₹1,000 and you fill at ₹1,001, you're off by 0.1%. That error is small, it's one-directional, and it doesn't change what position you hold.
An option-selling copy has to match strike, expiry and timing across two or more legs at the same time. That adds points of failure, and the failures don't add up neatly. They compound, because the premium on each leg depends on spot, implied volatility and time left, all of which are moving while your orders are in flight.
On expiry day, the effect is sharper. Theta is at its steepest, so premium drains by the minute. Gamma is high near the money, so a small spot move changes an option's price by a lot. Where a long-dated option shrugs off a 60-second delay, a NIFTY weekly option on expiry morning doesn't. We've covered the decay side in our look at the NIFTY expiry-day premium clock, and the point carries straight over to copying: the cost of being late rises as the day goes on.
The Fill-Timing Problem, Worked Through
Here's an illustrative example. The numbers are made up to show the mechanics, so read them as a teaching case and not as recorded trades.
Say NIFTY is at 24,500 at 10:00 IST on a weekly expiry day. The source account sells a short strangle: the 24,800 call and the 24,200 put. The source fills the call at ₹62.00 and the put at ₹58.00. That's 120 points of combined premium. At a lot size of 65, one lot collects 120 × 65 = ₹7,800.
Now add a copy delay of 75 seconds. During those 75 seconds NIFTY ticks up 18 points to 24,518, and implied volatility on the near-the-money strikes eases a little. Because the call is now a bit closer to the money, its premium rises. The put moves further away, so its premium falls. Suppose the follower's fills come back at ₹66.00 for the call and ₹53.00 for the put.
The combined premium is 119 points. That's almost identical to the source's 120, so if you only look at the total, the copy seems fine. It isn't. The source is short a call with a 24,800 strike when spot was 24,500, which puts the call 300 points out of the money. The follower sold the same strike, but from a spot of 24,518, so it's 282 points out. The put went the other way: 300 points out for the source, 318 for the follower. The follower's position is a touch more exposed on the upside and a touch more cushioned on the downside than the one being copied. The position is no longer the same.
A skew like that is small on a calm morning. On a day when the index is trending, a 75-second gap can be 40 or 50 points, and the same structure turns into a different trade with a different centre of gravity. The follower thinks it's holding a delta-neutral strangle that someone vetted. It's holding something close to that, with an extra bias nobody chose.
Why the total premium hides the damage
This is the part that makes copy-trading dashboards misleading. Most show something like "copied successfully" with a combined entry price. If the total matches, the dashboard shows green. But a strangle's risk lives in the individual legs: how far each short strike sits from spot, and how much premium each has left to give back as time passes. Two strangles with the same total premium can have very different risk profiles.
When we run entries through our own backtest engine's fill model, we look at each leg separately for exactly this reason. In our experience, an entry that looks fine in aggregate can hide a leg that filled well and a leg that filled badly, and the bad leg is what shapes the day. We've seen the same pattern when readers send us screenshots of a copied trade and ask why their day looks nothing like the source's.
Slippage on Two Legs Is Not Twice the Slippage on One
For a single equity order, slippage is the gap between the price you expected and the price you got. For a two-leg strangle, slippage has an extra dimension, which is which leg slipped.
Take the same example, with a twist. The follower's call fills almost instantly at ₹62.50. But the put order sits unfilled for 90 seconds because the follower's broker rejects the first attempt on a price band and the platform retries. By the time it fills, spot has dropped 25 points, and the put is worth more. It fills at ₹71.00. The follower has now sold the call at ₹62.50 and the put at ₹71.00, for 133.5 points of total premium.
That looks like a better entry than the source's 120 points, and a naive comparison would say so. But the put was sold after the market had already moved toward it. The follower collected extra premium because the position carried extra risk: spot was now much closer to the put strike when the put went on. The source's strangle was balanced at entry. The follower's wasn't. A move that costs the source almost nothing could hurt the follower more.
This is the compounding problem. One leg fills well and the other fills badly, and what you end up running is a different position from the one being copied, not a close approximation of it. On a single-instrument copy there's no such thing as "one leg filled and the other didn't."
Partial fills and orphan legs
The worst outcome isn't a slow fill. It's a fill that never completes. If the call leg fills and the put leg is rejected for margin, price-band or liquidity reasons, the follower is left holding one naked short option. The source holds a strangle. You hold a directional bet you didn't choose, in an instrument that can lose many times its premium.
Good platforms try to prevent this with basket orders or leg sequencing, buying the protective or hedging leg first. Not every copy-trading setup does, and the behaviour often isn't documented where a follower can see it before signing up. If you're evaluating a service, ask directly what happens when one leg of a multi-leg order fails. If the answer is vague, assume the worst case.
Account-Size Mismatch: When "Scaled" Doesn't Fit
Scaling a trade by a ratio sounds mathematical and clean. In practice it collides with lot sizes and margin.
Another illustrative case. The source account has ₹40 lakh and sells 20 lots of the strangle. Your account has ₹4 lakh, so the platform scales to 2 lots. Suppose the strangle needs roughly ₹1.2 lakh of margin per lot (the real number changes with volatility and exchange rules, so check your broker's margin calculator, and our piece on the NSE margin calculator versus broker margin explains why the two often differ).
Two lots needs about ₹2.4 lakh. You have ₹4 lakh, so the order goes through. Fine so far. But what does your account look like at that point? You've used 60% of your capital on one position. The source used well under half of theirs, because they sized for a book with room to survive a bad day. Scaling the lots proportionally didn't scale the headroom. You're running a much fuller account.
Now suppose your ratio rounds badly. At ₹2.5 lakh of capital, a 1:16 ratio gives 1.25 lots, which rounds to either 1 or 2. Rounding up to 2 lots needs ₹2.4 lakh of margin against ₹2.5 lakh of capital. You've barely got ₹10,000 of buffer. One adverse move in either leg raises the margin requirement through mark-to-market, and the broker's risk system can reject further orders, force a partial square-off, or flag the account. The source, with deep headroom, never sees any of that. They sit through the same move comfortably.
Lot size is not a ratio
NIFTY's lot size is 65. You can't take 1.25 lots. Exchanges change lot sizes from time to time, and a platform that scaled based on an old figure can produce orders that don't match what you expect. Whatever your platform calls "proportional," the real position is a whole number of lots, and the rounding error can be 20% or more of your intended size when your account is small. That's a bigger deviation than any fill-price difference.
Exits are copied too, and exits are where sizes matter most
People focus on entries and forget the copy applies to exits and stop-losses as well. If the source has a stop-loss on each leg, your account has to replicate it, at the right trigger, with similar latency. A stop that triggers at the same index level but fires 90 seconds late on your side can lose materially more in a fast market. On expiry day, option premiums can double or halve inside a couple of minutes, which is why we spent so much time on why the same strike prices differently on a different day. A late stop doesn't just cost a little extra. It can turn a planned small loss into the kind of loss the source's stop was designed to prevent.
Why Options Make the Problem Bigger Than Equities
It's worth putting the comparison side by side in plain terms, since it's the heart of why copy trading deserves more suspicion in options.
An equity copy has one instrument, one price, and slippage that's usually a fraction of a percent. A late fill changes your cost basis a little and nothing else about the position.
An options copy has two or more instruments, each with its own price, its own liquidity and its own sensitivity to spot, volatility and time. A late fill changes the cost basis of each leg differently, which changes the balance between the legs, which changes the risk of the whole position. You can't fix it by averaging, because the error isn't a single number.
There's also the liquidity side. Far-out-of-the-money strikes are thinner than at-the-money ones, and a platform that sends a market order for an illiquid strike can fill well away from the last traded price. Source accounts trading size sometimes get better fills than a retail follower because of how they route orders or how deep they trade. The follower, copying later and in a thinner slice of the book, consistently gets the leftovers. If you want the longer version of this argument for multi-leg structures, our article on why there is no zero-risk option strategy walks through the same execution, liquidity and cost layers for box spreads.
How the Source Itself Might Mislead You
So far we've talked about what goes wrong between the source and the follower. There's a second problem upstream: what you're being shown about the source.
A leaderboard of returns tells you what the source's account earned. It doesn't tell you what a follower would have earned from copying them. Those two numbers differ by every issue above: latency, slippage, rounding, margin headroom. A source that looks excellent on its own fills can be mediocre to copy, particularly if its edge depends on getting fills at the moment a signal fires.
Second, a track record from a short window, or from a single regime, doesn't say how the strategy behaves when conditions change. Option-selling results are especially lumpy. A run of calm weeks followed by one violent day can erase most of the profit, which is the shape of risk that a three-month leaderboard is almost designed to hide. Our own write-up on whether algorithmic trading is profitable, using our own data gets into why the distribution of outcomes matters more than the average.
Third, there's survivorship. Platforms show you accounts that are still active and doing well. The ones that blew up quietly disappeared from the list, so the sample you're choosing from is already filtered toward luck.
Where EliteAlgo Stands
We'll say this directly, because it matters for how you read everything above. EliteAlgo is a proprietary trading desk. We trade with our own capital, using rules we've tested in our own backtest engine, and we publish research. We don't run a signal service, we don't sell tips, and we don't offer a copy-trading product for others to mirror live. We aren't a SEBI-registered investment adviser or research analyst, and nothing on this site is advice. If you want to understand where that line sits, our piece on SEBI RA, RIA and analytical software explains the difference.
That also means we have no commercial reason to talk you out of copy trading. We just think the mechanics are worth understanding before you hand over capital. Per the SEBI Investor Charter, investors are entitled to clear information about the risks of a product and the services they sign up for. You can read the SEBI Investor Charter for what the regulator lists as your rights. A copy-trading provider that can't explain its latency, its multi-leg failure handling and its margin treatment hasn't given you the information you need to decide.
How We Looked at This
A word on methodology, since we'd rather be clear about what is evidence and what is illustration. The worked examples above are illustrative: round numbers chosen to show the mechanics, not a record of live copy trades, and not a sample of real followers. The reasoning behind them comes from how our own backtest engine models entry fills, where we compare an idealised entry price against a delayed one across expiry days and look at the legs separately. We haven't run, and aren't claiming, a measured study of any specific copy-trading platform. If a provider publishes real follower-versus-source fill data, that would be far better evidence than our examples, and it's worth asking for.
What we're confident about is the structure of the problem. Premium decays and moves with spot. Multi-leg positions have more failure points than single-leg ones. Margin doesn't scale like lots do. Those are properties of the product, not opinions.
A Practical Checklist Before You Copy Anything
If you're still considering a copy-trading service for option selling, here is what to check, in roughly the order it matters.
First, ask for the measured latency between a source fill and a follower order, and ask whether it's an average or a worst case. An average of two seconds with a worst case of 40 tells you very different things. Second, find out how multi-leg orders are sent: as a single basket, or leg by leg, and which leg goes first. Third, ask what happens to the second leg when the first one fills and the second is rejected. Fourth, work out your own margin headroom after scaling, not just whether the order passes. If a 20-point adverse move in NIFTY would push you toward a margin call, the sizing is too aggressive for your account whatever ratio the platform picked.
Fifth, check how stop-losses are handled. Are they placed as orders on your side, copied as events, or triggered by the platform? Each has a different failure mode. Sixth, look at what the provider says about slippage in its own terms. If it never mentions it, that tells you something.
Finally, before any live capital, paper trade the copy. Run the service in a simulated or tiny-size mode for a few weeks of expiries. Log the source's fill and your fill for every leg, with timestamps. Compute the gap in points per leg and the difference in the combined position's distance from spot. That log is the only evidence that matters, because it measures your pipeline and your broker on your days. It's the same discipline we describe in our piece on paper trading an option-selling algo, and the point there applies equally to anything you'd mirror.
What We'd Do Instead
If the aim is to learn option selling without learning it the expensive way, copying someone else's trades is the hardest route to understand, because you don't see the reasoning, only the orders. A more useful path is to learn the structure yourself: how a strangle's legs behave, why expiry day is different, how margin works for your broker, and what your own fills look like on small size. Our breakdown of the disadvantages of algo trading covers the execution, data and discipline risks that apply to any automated approach, including a copied one, and it's worth reading before you automate anything.

Backtesting a rule-based approach and then testing it on paper gives you something copy trading can't: the ability to see why a position lost, and to change the rule. Our comparison of paying for an option-trading course against backtesting yourself makes the same case for building your own understanding before spending on someone else's.
None of this means copy trading is always a bad idea. For simple, slow, single-instrument trades it can be a reasonable convenience. For option selling, especially on expiry days, it asks a lot of a pipeline whose weak points the marketing rarely discusses. Go in knowing what doesn't copy.
Frequently Asked Questions
Does copy trading work for options?
It works for the direction and structure of a trade, meaning the same strikes and expiry, when execution is fast and both accounts have similar margin headroom. It works less well on fill price, timing and sizing, because an option-selling position has several legs that all need to fill near the source's prices. Per our own fill-model work, the combined premium can look right while the individual legs sit in different places relative to spot.
Why does my copied trade fill differently from the source trade?
Because your order reaches the exchange later. The source order is placed, the platform sees it, calculates your size and sends your order through your own broker. In that gap spot, implied volatility and time decay all move, so each leg's premium changes by a different amount. On expiry day, when premium drains by the minute, even a delay of a minute or so can matter.
Is copy trading safe for multi-leg option strategies?
It carries more points of failure than copying a single equity order. One leg can fill while another is rejected or delayed, which leaves you holding a different position from the source. Ask any provider how it sends multi-leg orders and what happens when one leg fails. If the answer is unclear, treat that as a warning and paper trade the copy first.
What is slippage in copy trading?
Slippage is the gap between the price the source account got and the price your account got for the same order. In copy trading it comes from latency, thinner liquidity at your size and rounding of the scaled quantity. For a strangle you should measure it per leg, because two legs with the same total premium can leave you with a very different risk profile.
Should beginners use copy trading to learn option selling?
We'd say no, at least not as the main route. You see the orders but not the reasoning, so you can't tell why a position worked or lost. Learning the structure yourself, backtesting a rule and paper trading it gives you something you can change. If you do try copy trading, use small size and log every source fill against your own.
What happens if my account is much smaller than the source account?
The platform scales the lots down, but lot sizes are whole numbers and margin does not scale in a straight line. A small account can end up using a far bigger share of its capital than the source does, with very little room for an adverse move. Check your margin after scaling and after a 20-point adverse move in NIFTY, not just whether the order passes.
Does EliteAlgo offer a copy-trading or signal service?
No. EliteAlgo is a proprietary trading desk. It trades its own capital with its own backtested rules and publishes research as analytical software, not investment advice. It does not sell tips, signals or a copy-trading product.
EliteAlgo is a proprietary trading desk sharing its own research and backtest framework as analytical software, not investment advice. We trade NIFTY and SENSEX expiry-day option selling with our own capital and our own backtest engine, and nothing above is a recommendation to use any specific strategy, platform or service. Paper trade first.