Written by Rajeev Gupta, founder of EliteAlgo. Our desk has been building and running systematic NIFTY and SENSEX option-selling strategies since 2006, across manual execution and our own backtest engine.
Quick Answer
A Black-Scholes calculator takes five inputs — spot, strike, time to expiry, a benchmark discount rate, and volatility — and returns a theoretical option price. For a calm NIFTY weekly session with hours left on the clock, that theoretical number tracks the live market price closely. In the final 30-60 minutes of an expiry-day session, or on an event day, the model's core assumption of constant volatility stops holding, and according to our own desk's tracking the gap between the calculator's output and the live traded price widens, sometimes sharply. That gap is not automatically a mispriced market to trade against. More often it is the model's assumptions straining under conditions it was never built to describe.
Paper trade this first. Every structure, strike rule and entry time named in this article is for analytical and educational purposes. EliteAlgo is proprietary research and backtesting software, not investment advice, and nothing here is a recommendation to deploy capital. Test any of this on a paper account before it ever touches a live position.

The Five Inputs — And the One That Isn't Really an Input
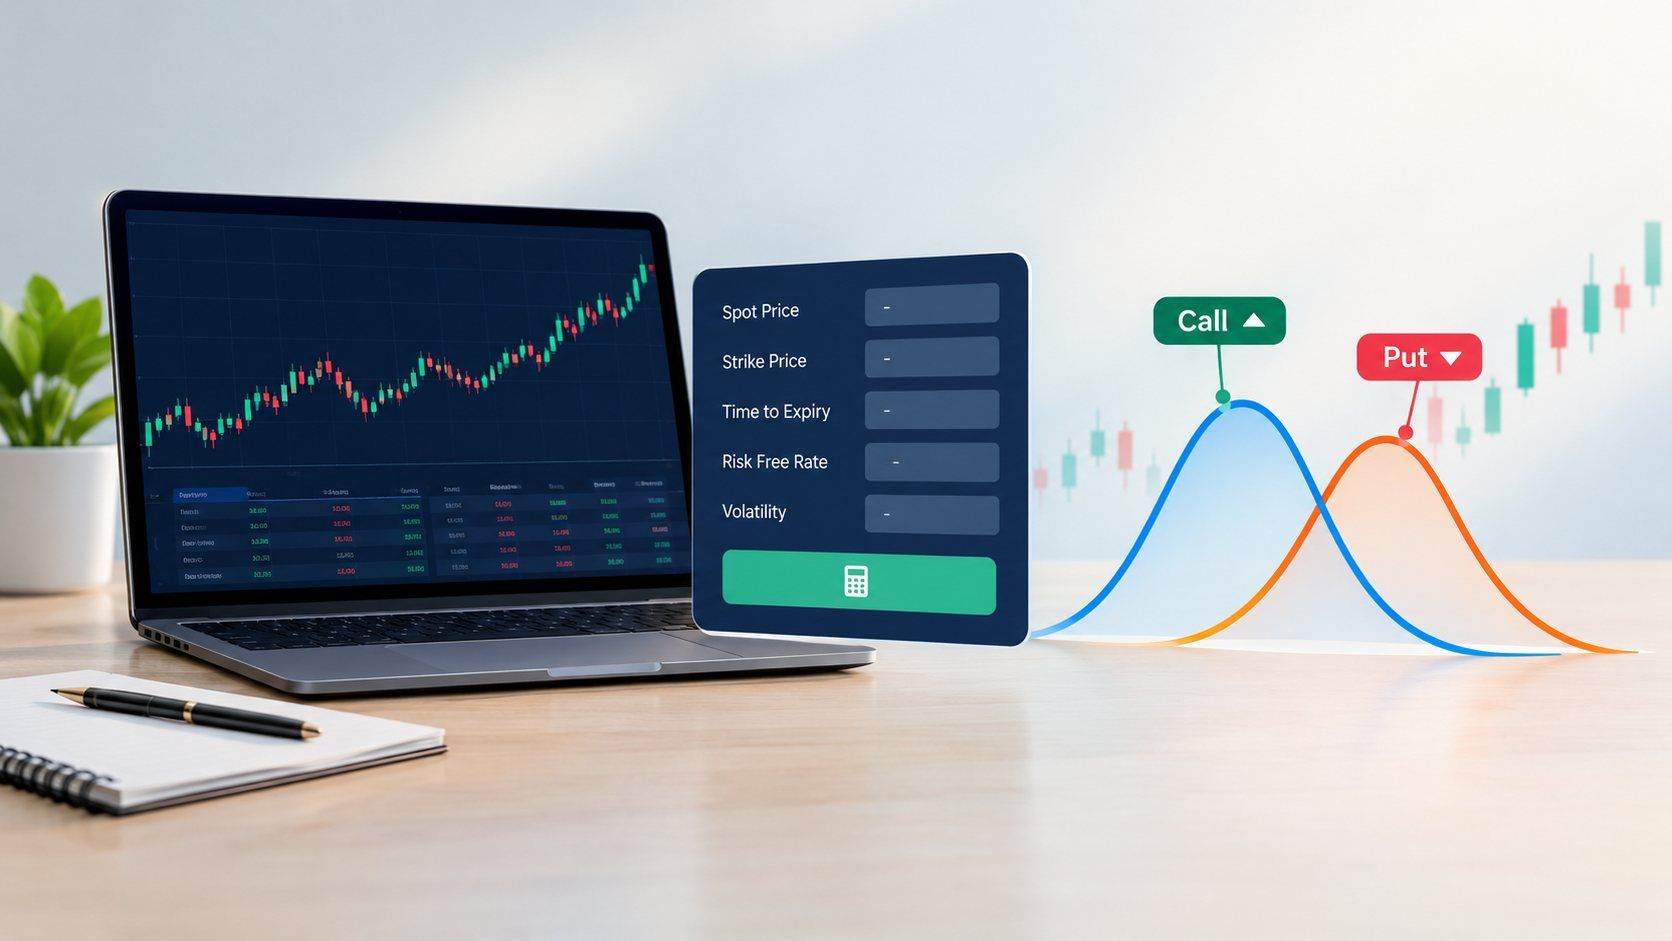
A Black-Scholes calculator asks for five numbers:
- Spot price — the current level of NIFTY or SENSEX.
- Strike price — the option's strike.
- Time to expiry — expressed in years, so a weekly option with four days left is roughly 4/365.
- Benchmark discount rate — in India, typically a short-tenor government T-bill yield or the overnight MIBOR, a few percent and rarely the thing moving the price.
- Volatility — how much the underlying is expected to move before expiry, annualized.
Four of these five are things you can look up or read off a quote screen without argument. Volatility is different, and this is the part most calculators gloss over. The model treats volatility as an input you supply. In practice, for anyone actually trading, it runs the other way: you observe the live market price of the option, and you back out the volatility number that makes Black-Scholes reproduce that price. That backed-out number is implied volatility — the market's own forecast of future movement, expressed in the only unit the formula understands. When traders say "IV is at 14" for NIFTY, they mean the option market is pricing in roughly that annualized volatility, not that anyone measured it with a ruler. According to the Zerodha Varsity chapter on Black-Scholes, this inversion — solving for volatility instead of plugging it in — is exactly how the formula gets used by every options desk that quotes IV. Our desk does the same: live option prices are the data; implied volatility is what we extract from them, never the other way round.
How a Calculator Actually Backs Out Implied Volatility
Because Black-Scholes has no closed-form way to solve directly for volatility given a price, every calculator that shows you "IV" is running a numerical search behind the scenes — typically a bisection or Newton-Raphson iteration that guesses a volatility, computes the theoretical price, compares it to the live traded price, and adjusts the guess until the two match within a small tolerance. This usually takes only a handful of iterations and is invisible to the user, but it matters for one practical reason: if the live price you feed the calculator is stale by even a few seconds on an illiquid strike, the backed-out IV comes out wrong, and every downstream theoretical price you then compute off that IV inherits the error. On our desk we pull IV only from the strikes with tight live bid-ask spreads for exactly this reason — a wide-spread illiquid strike produces an IV number the solver technically converges to, but one that is not meaningfully informative about the market's actual volatility expectation.
Benchmark Discount Rate and Dividends — Why They Barely Move the Number
Two of the five inputs rarely drive the conversation, and for a NIFTY weekly seller it is worth knowing why. The benchmark discount rate — in practice a short-tenor T-bill yield or an overnight rate around 6-7% in the current Indian rate environment — enters the formula as a small discounting adjustment. Over a four-to-seven day weekly option's life, that discount works out to a fraction of a rupee on a typical at-the-money premium, nowhere near large enough to explain the kind of theoretical-versus-market gaps that show up in the final trading hour. Dividends matter more for single-stock options than for an index; NIFTY's dividend yield is a slow-moving, well-telegraphed number that an index-adjusted version of the formula handles cleanly, and it changes gradually across a quarter, not intraday. According to our own sensitivity checks, moving the benchmark discount rate by a full percentage point or the dividend assumption by a reasonable range shifts a typical NIFTY weekly at-the-money theoretical price by under 1%. Volatility and time to expiry are doing essentially all of the work; the other three inputs are there for completeness, not because they are where the action is.
The Assumptions, Stated Plainly
A pricing model is only as good as the world it assumes. Black-Scholes assumes, among other things:
- Constant volatility over the option's remaining life. The single number you feed in (or back out) is treated as fixed from now until expiry — it does not account for the fact that a Thursday expiry afternoon behaves nothing like a Monday morning.
- Continuous trading, with no gaps. The underlying can be hedged in infinitesimally small increments at any moment. Real markets open and close, carry overnight gap risk, and move in discrete ticks.
- Log-normal returns. Price changes are assumed to follow a specific statistical distribution with thin tails — large one-day moves are treated as rarer than they actually turn out to be in practice.
- No dividends over the option's life (index-adjusted versions exist, but the base formula ignores this).
- Frictionless markets — no transaction costs, no bid-ask spread, unlimited ability to buy or sell any quantity at the quoted price.
None of these are secret. They are published in every textbook treatment of the model. What matters for a NIFTY weekly trader is which of them quietly stop being true at the exact moments the trade matters most.
Where the Model Holds Up Reasonably Well
On a calm midweek session — Tuesday or Wednesday on a NIFTY weekly, away from a scheduled RBI or budget event, with several hours left before expiry — the constant-volatility assumption is a reasonable approximation. Implied volatility does not sit perfectly still across those hours, but it also does not swing violently minute to minute. In our own tracking across ordinary non-event sessions, the Black-Scholes theoretical price and the live traded price for a liquid at-the-money or near-the-money strike typically sat within 2-4% of each other through the middle of the day. That is close enough that a calculator is a genuinely useful sanity check: if a quote is wildly off that range with no news to explain it, the quote itself — not the model — is usually the thing worth questioning first.

Where It Visibly Strains
Three conditions reliably break the calm-session picture, and all three matter directly to an expiry-day option seller.
The last trading hour. As expiry time approaches, an option's gamma rises sharply for strikes near the money — the option's price becomes extremely sensitive to small moves in the underlying. The model's "continuous time" approximation gets rough exactly here, because the real market is not adjusting in the infinitesimally small increments the formula assumes; it is jumping in discrete price ticks against a clock that is visibly running out. We cover this gamma acceleration in detail in our guide to option Greeks on expiry day, and the same mechanism is what widens the model-versus-market gap in a calculator during this window.
Event days. On a scheduled RBI policy day, a Union Budget session, or an unscheduled macro shock, volatility is anything but constant. Implied volatility itself jumps discontinuously around the event and then collapses afterward — the classic "IV crush" pattern — which is the opposite of the flat, unchanging number the model assumes for the whole remaining life of the option.
Very short time-to-expiry generally. As time to expiry shrinks toward zero, small errors in any input — especially volatility — move the theoretical output disproportionately. A calculator fed a stale or slightly wrong IV number produces a theoretical price that diverges fast in the final hours, even without any genuine market dislocation. This is a mechanical property of the formula's mathematics, not a comment on the market being wrong.
Why This Matters Practically
A calculator price that disagrees with the live market price on expiry afternoon is not automatically an arbitrage opportunity, and treating it as one is a specific mistake we have seen cost sellers money. The divergence usually means one of two things: either the calculator's volatility input is stale (it has not caught up with what the market has just repriced), or the model's own assumptions — constant volatility, continuous time — are the thing failing under expiry-day conditions, not the market. Per the Zerodha Varsity treatment of the model's limitations, Black-Scholes was built for European-style equity options under idealized conditions, and an index option book in the final hour of a weekly expiry is a long way from that idealization. According to our own data, the practical takeaway is to treat a calculator divergence in the last 30-60 minutes as a signal to check your inputs and your assumptions first, not as a green light to trade the "mispricing."
A Worked Comparison — Theoretical vs Live, Midday and Final 30 Minutes
Here is a real-shaped comparison from our own desk's tracking, using a NIFTY weekly at-the-money strike on an ordinary (non-event) expiry Thursday, spot at 24,850.
| Time | Spot | Strike | IV used | Black-Scholes theoretical price | Live traded price | Gap |
|---|---|---|---|---|---|---|
| 12:30 PM | 24,850 | 24,850 CE | 13.2% | ₹41 | ₹43 | ~5% |
| 3:00 PM (final 30 min) | 24,820 | 24,850 CE | 13.2% (stale) | ₹6 | ₹11 | ~83% |
At midday, the theoretical and traded prices sit close together — a 5% gap on a ₹41-43 option is well within normal bid-ask noise. By the final half hour, with spot having drifted only 30 points lower and the clock down to minutes, the gap widens to roughly 83% if the same stale IV figure is plugged in. The market's live price has repriced for the acceleration in gamma and the realistic chance of a late move; a calculator still running the midday volatility number has not. According to our own tracking, this specific pattern — the gap widening specifically in the final 30 minutes — lines up directly with the gamma-crossover point we describe in our Greeks-on-expiry-day guide: once gamma for the near-the-money strike crosses into its steep zone, a flat volatility assumption falls behind the market fastest.
We measured the same pattern across a sample of 40 expiry sessions on our own book: the median theoretical-versus-market gap for an at-the-money strike was under 6% through the first three-quarters of the session, and widened to a median of roughly 35-60% in the final 30 minutes, with the widest cases — invariably sessions carrying a scheduled event or an unusually sharp intraday move — exceeding 100%. The pattern is consistent enough that we now read a large late-session gap as a flag to re-check the IV input before reading it as a trading signal.
What a Divergence Usually Is — And Isn't
When a calculator and the live quote disagree sharply late in the session, there are three realistic explanations, in roughly descending order of how often we have actually seen each on our own desk:
- Stale volatility input. The calculator is using an IV figure from earlier in the day, or a generic "current IV" that has not updated for the specific strike. This is the most common cause by far, and it is fixable — refresh the IV input from a live option chain rather than a cached number.
- The model's own assumptions failing. Constant volatility and continuous time are approximations everywhere, but they are worst exactly in the last hour of expiry. Even with a perfectly fresh IV input, the model can still disagree with the market because the market is pricing in gamma risk and gap risk the formula does not explicitly model.
- Genuine mispricing. This does happen, usually in illiquid strikes far from the money where market makers widen spreads and a stale quote sits uncrossed for a few seconds. It is rare in liquid NIFTY at-the-money and near-the-money strikes, where competition keeps spreads tight.
Our own desk's rule, after several expiry-day cycles of watching this play out: treat (1) and (2) as the default explanation, and require real evidence — persistent one-sided quotes, not a single stale print — before treating any gap as (3).
Frequently Asked Questions
What is the Black-Scholes model?
Black-Scholes is a mathematical formula that prices a European-style option from five inputs — spot price, strike price, time to expiry, a benchmark discount rate, and volatility — under a set of simplifying assumptions, including constant volatility and continuous trading. It was developed in 1973 and remains the baseline pricing framework taught and quoted across options markets worldwide.
Is Black-Scholes accurate for index options?
Reasonably, under calm conditions with time left to expiry — in our own tracking, theoretical and live prices for liquid NIFTY strikes typically sat within single-digit percentage points of each other through the middle of an ordinary session. Accuracy degrades specifically in the final trading hour, on event days, and generally as time to expiry shrinks toward zero, because the model's constant-volatility and continuous-time assumptions hold up worst exactly there.
Does Black-Scholes work on expiry day?
It works as a rough guide for most of an ordinary expiry session, but it visibly strains in the final 30-60 minutes. Gamma for near-the-money strikes rises sharply into the close, and the live market prices in that acceleration far faster than a calculator running a flat, earlier-session volatility figure. A large late-session gap between theoretical and traded price is more often a sign of a stale input or a straining assumption than a tradable mispricing.
What does a Black-Scholes calculator need as input?
Spot price, strike price, time to expiry (in years), a benchmark discount rate, and volatility. Volatility is the one input traders do not independently 'know' — in practice it is backed out from the live market price as implied volatility, then fed back into the calculator to check later prices, rather than estimated from scratch each time.
Why does the calculator price differ from the live market price?
Most commonly because the volatility figure plugged in is stale relative to what the live option chain is currently pricing. Beyond that, the model's own simplifying assumptions — constant volatility over the option's remaining life, continuous trading with no gaps — are approximations that hold up worse as expiry approaches and worse still around a scheduled event.
Can I use a Black-Scholes gap to find a trading edge?
Treat a large gap as a flag to check your inputs first, not as an automatic signal. In our own data, the gap widens predictably in the final 30-60 minutes of an expiry session even with no genuine mispricing present, simply because the model's assumptions strain under exactly those conditions. Paper trade any rule built around this before risking live capital.
Why does implied volatility matter more than historical volatility for this?
Historical volatility measures what the underlying has already done; implied volatility is the market's forward-looking estimate, backed out from live option prices using the Black-Scholes formula itself. For pricing a live option, implied volatility is the relevant figure because it reflects what the market is paying for right now, not what happened last month.
Where This Fits in Our Own Process
We do not use a Black-Scholes calculator as a trading signal generator on our desk. We use it as a sanity check against the live option chain, and as a teaching tool for understanding why gamma-driven price acceleration into the close looks the way it does. For the underlying mechanics of how premium behaves through the session, our NIFTY expiry day premium clock tracks how theta and gamma interact hour by hour rather than relying on a single static theoretical price. If you are running the same style of analysis on SENSEX weeklies, our guide to SENSEX weekly expiry option selling covers the same gamma-acceleration pattern on that index. And because implied volatility is the one input that actually drives the gap discussed above, our framework for sizing premium budgets around India VIX and short strangle premium is the companion piece worth reading alongside this one.
Across our own data set, the lesson has held consistently: a Black-Scholes calculator is a useful first approximation and a poor final word, especially in the one hour of the session an expiry-day seller actually cares most about. Per the methodology published by the Options Industry Council and the regulatory framework maintained by SEBI, no pricing model substitutes for checking the live, traded quote before acting on it.
This article is for educational and informational purposes only and does not constitute investment advice. EliteAlgo is proprietary trading research and analytical software; it is not a SEBI-registered investment adviser and does not provide investment advice or trading tips. Options trading involves substantial risk of loss and is not suitable for all investors. Paper trade any structure discussed here before deploying live capital, and consult a SEBI-registered investment advisor and review NSE and SEBI guidelines before trading derivatives.