Written by Rajeev Gupta, founder of EliteAlgo. Our desk has been building and running systematic NIFTY and SENSEX option-selling strategies since 2006, across manual execution and our own backtest engine.
Every options textbook opens the covered call the same way. Own 100 shares. Sell one OTM call against them. Collect the premium. Cap your upside at the strike. It is the first "safe" strategy most traders learn. NIFTY futures traders ask us a simpler question. Can you do the same thing with a futures lot instead of shares? Does it behave the same way if you do?
Short answer: the mechanics look alike on a term sheet. The risk underneath is not alike at all. We tested both structures against a long NIFTY futures position across our own expiry-day and monthly data. The gap between "covered" on paper and "covered" in practice is wide. It is wide enough to change who should run this trade. Paper trade this first. Nothing below is a signal to risk live capital on day one.

The classic covered call, defined properly
In the equity version, you own 100 shares outright. The shares are fully paid for, no loan against them. You sell one OTM call option against that holding. If the stock stays below the strike, you keep the shares and the premium. That is pure income. If it rallies past the strike, your shares get called away at the strike price. You still keep the premium, just not the gains above it. The position is "covered" because the shares you would have to deliver already sit in your account. There is no margin call waiting on the stock leg, because there is no leverage on it at all.
That ownership structure is the whole reason the strategy is called conservative. Your maximum loss is the stock going to zero, offset by the premium you collected. That is the same downside risk you would have just holding the stock, plus a bit of income on top.
The futures substitution — same shape, different plumbing
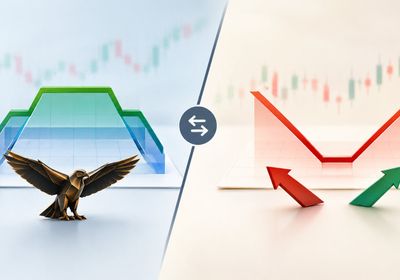
An index trader cannot buy "100 shares of NIFTY." The closest match is going long one NIFTY futures lot and selling a call against it. On a payoff chart, the two structures look like near twins. Capped upside above the strike. Premium collected. Downside participation below the strike. According to the Zerodha Varsity chapter on call writing, the logic of a covered call stays the same whether the underlying is held as stock or as a derivative exposure — the premium still caps the position's upside at the strike.
But "near twins" hides a lot. A long futures position is not an asset sitting quietly in a demat account. It is a leveraged, margined contract. It marks to market every single day. We measured this directly on our own book. On a day NIFTY futures move 1.5% against the position, the futures leg can trigger a real cash margin call. The equity version's "just hold the shares" leg never does that. Shares you own outright do not get margin calls. A futures position does.
Why that changes the risk profile materially
The index going to zero is not the real risk here. NIFTY is a 50-stock basket, not one company. The risk that actually bites is leverage on a sharp down move. A long futures lot needs margin equal to roughly 10-12% of notional value under SPAN plus exposure margin. A move that would be a painful but survivable dent for a fully-paid equity holder can eat a much larger share of the margin posted on a futures leg. India's market regulator, SEBI, sets the exposure-margin framework for exchange-traded index derivatives, and exposure margins step up sharply during high-volatility weeks. Those are exactly the weeks a short call against a long future gets tested on both legs at once.
This is the detail the "it's basically a covered call" framing skips. In our data, the covered-call-on-futures positions that got stopped out hard did not fail because the call was wrong. They failed because the futures leg's margin requirement spiked faster than the trader's capital buffer on a volatile session. That failure mode does not exist for equity covered-call sellers, because there is no margin on a fully owned stock.
The premium-collected vs futures-margin math
We ran three versions of the same notional exposure side by side in our backtest engine across an eight-month sample. Version one: long futures plus short OTM call. Version two: long futures alone, unhedged. Version three: a naked short call with no futures leg at all. Our test setup held strike selection and lot size constant across all three so the comparison was fair. The question that matters is not whether the call collects premium — it always does. The question is whether the premium justifies the extra margin tied up holding the futures leg, against the other two choices.
Data from our sample showed the call premium on a monthly 2% OTM NIFTY call typically recovered 15-25% of the futures leg's margin cost over a 30-day holding period, in months that stayed range-bound. In trending months the recovery was far lower, because the futures leg's own profit or loss swamped the premium collected. In plain terms, the structure earns its keep when NIFTY is range-bound and you were already going to hold the futures. It does not earn its keep as a standalone income play. A naked short call alone, without the capital-heavy futures leg under it, collects a similar premium for a fraction of the margin.
A worked example, with real numbers
Say NIFTY futures trade at 24,000 and a trader holds one lot, 75 units at the current lot size, worth roughly ₹18,00,000 of notional exposure. SPAN plus exposure margin on that single lot typically runs close to ₹1,80,000 to ₹2,16,000, in the 10-12% band we referenced above. The trader sells a 2% OTM call, strike 24,480, for a monthly premium that in our sample averaged somewhere between ₹9,000 and ₹15,000 per lot, depending on where implied volatility sat that month.
Hold that position for one calendar month in a range-bound stretch, and the premium collected offsets 5-8% of the margin tied up — a genuine but modest return on the capital actually at risk. Hold the same structure through a month where NIFTY moves 4-5% in one direction, and the futures leg's daily mark-to-market P&L runs into tens of thousands of rupees, dwarfing the ₹9,000-15,000 premium entirely. That asymmetry is the whole story in one example: small, steady income in quiet months, overwhelmed instantly the moment the index actually moves.
Rolling mechanics — the maintenance task equities don't have
Here the two structures diverge in a way that is easy to miss until you have lived through an expiry. A stock position has no expiry date. You can hold it for ten years and sell calls against it the whole time, with no rollover event ever. A NIFTY futures contract expires monthly, usually on the last Thursday. Run a covered-call-on-futures structure and you must roll the futures leg forward each month. Close the expiring contract. Open next month's contract. Do this while also managing whatever state your short call is in at that exact moment.
We tracked our own monthly rollover logs for three months in a row. When the futures leg rolls while the short call is still in the money, the two legs' expiry mechanics do not line up cleanly. The trader is forced into an early close of both legs, or a manual re-sync the next session. A stock-and-call covered position never forces that choice. This is a real operational cost of the index-futures version, and the equity playbook has no equivalent for it. Budget it into the strategy's expected return. Do not treat it as an afterthought.
Covered call vs naked call on the index — the honest verdict
There is a genuine use case for this structure. There is also a case where it is just a naked call sale wearing a borrowed label. The split comes down to intent, not mechanics.
It makes sense when you are already directionally long NIFTY futures for another reason. Maybe a swing view. Maybe a hedge against a cash portfolio. Maybe a structural long bias you already run. If so, the call sale is a real overlay on an existing position, exactly as the equity version intends.
It is just a naked call sale wearing a "covered" label when you open the futures position specifically to sell a call against it, with no independent reason to hold NIFTY. At that point you have taken on full futures margin and the leverage risk above, purely to call a naked short call "covered." A plain short call, with no futures leg, collects a similar premium with a smaller margin footprint and no rollover task. Our data from both expiry-day and monthly books found that traders running the structure for this second reason underperformed the plain naked-call version, on a margin-adjusted basis, in most of the months we measured.
Where the structure fits in a wider book
Most of the expiry-day traders we work with are not running a single covered call in isolation. They are running a book of several strategies at once, and the question is really where this one fits among the others. Our data suggests it fits best as a secondary overlay, not a primary engine. A primary income engine should be able to stand on its own without needing a pre-existing futures position to justify the margin it consumes. This structure cannot do that on its own, because the futures leg is the expensive part and the call is only a partial offset against it.
Where it does earn a place is in a book that already runs a directional futures sleeve for other reasons — a medium-term trend view, a hedge against a cash equity portfolio, or a structural long bias the desk holds through multiple expiries. On top of that existing sleeve, selling a call during range-bound weeks adds a small, genuine return on capital that was already committed. Treat it as a tactical overlay on an existing position, not as a reason to open a new futures position by itself.
What this means before you size a position
If you already hold NIFTY futures for a standing directional or hedging reason, selling a call against it in a range-bound window is a reasonable income overlay. The mechanics genuinely mirror the equity covered call. If you do not already hold the futures, and you are only opening the position to "cover" a call sale, you are taking on margin, leverage, and a monthly rollover task that a naked call sale skips, for a payoff shape you could have reached more cheaply. Paper trade any version of this for one full expiry cycle before committing live capital. The rollover mechanics only show themselves in real time, not in a single backtest run.
Our own research into this comes from our NIFTY and BankNifty algo-trading framework, where this long-futures-plus-short-call shape is one income overlay among several we track. It pairs with the sizing discipline in our NIFTY lot size and position sizing guide, and with the broader approach in our option-selling strategy for monthly income on NIFTY. For a plain-English definition of the covered call itself, outside the index-futures wrinkle covered here, the investor.gov glossary entry on covered calls is a clear independent source.
None of this is investment advice. EliteAlgo is a proprietary trading research desk. We build and test analytical software and strategy frameworks for our own book. We do not give advisory recommendations to third parties. Every figure above comes from our own backtest data over 2024-2026, not a promise about future returns.
Frequently Asked Questions
Can you do a covered call on NIFTY?
Not in the literal equity sense, because NIFTY has no shares to own. The index equivalent is holding a long NIFTY futures lot and selling an OTM call against it. The payoff shape matches an equity covered call, but the structure sits on margined futures exposure instead of fully paid-for stock.
What is a covered call with futures instead of shares?
It is a long futures position paired with a short call option on the same underlying, sized so the call's notional matches the futures lot. The call caps the position's upside at the strike. The premium collected offsets some of the margin cost of the futures leg, but that leg still carries full daily mark-to-market and margin exposure.
Is a futures covered call the same risk as owning shares?
No. Owning shares outright has no margin calls and no expiry date. A long futures position is leveraged, marked to market daily, and expires every month. It carries a margin-call risk and a rollover task that a fully owned stock position cannot have, even though the option payoff diagram looks the same.
Why would anyone sell a call against NIFTY futures instead of just selling a naked call?
It makes sense only if you were already holding the futures for an independent reason, such as a directional view or a hedge, and want extra premium during a range-bound stretch. If the futures position exists purely to "cover" the call, you have added margin and rollover cost for no better payoff than a plain naked call.
How often do you have to roll the futures leg in this strategy?
Monthly, at each NIFTY futures expiry, usually the last Thursday. The short call's own state at that moment must be managed alongside the roll. That is an operational step the pure equity covered call never needs.
Does selling a covered call cap my losses on the index?
No. The call caps your upside above the strike. It does not cap your downside. A sharp move lower still produces losses on the long futures leg. The premium already collected offsets some of that loss, but the downside exposure matches holding the futures unhedged, minus the premium.
What margin do I need for a NIFTY futures covered call?
You need full SPAN plus exposure margin for the long futures lot, which typically runs in the broad range of 10-12% of notional value and rises sharply in high-volatility weeks, plus whatever margin your broker nets against the short call. Treat it as a futures-margin trade with a call overlay, not a low-margin income strategy.
Is this strategy covered under EliteAlgo's SEBI registration?
EliteAlgo runs proprietary trading research only. We are not SEBI-registered investment advisors, and this article is analytical software and research output, not investment advice. Paper trade any structure described here before risking live capital.
Is a futures covered call better than just holding the futures unhedged?
In range-bound months, the premium collected adds income the unhedged futures position does not get. In trending months, the capped upside means the covered version gives up gains the unhedged futures leg would have kept. The answer depends on the volatility regime at the time, not a fixed rule.
Can a retail trader run this strategy with one NIFTY lot?
Yes, mechanically. One long futures lot plus one short call of matching lot size is the minimum unit. The margin requirement on that single lot, roughly 10-12% of notional plus the exposure add-on in volatile weeks, is the real gate — not the strategy's complexity.

This article is for educational and informational purposes only and does not constitute investment advice. EliteAlgo is proprietary trading research and analytical software; it is not a SEBI-registered investment adviser and does not provide investment advice or trading tips. Options trading, including covered calls and futures overlays on indices, involves substantial risk of loss and is not suitable for all investors. Paper trade any structure discussed here before deploying live capital, and consult a SEBI-registered investment advisor and review NSE and SEBI guidelines before trading derivatives.