People search "algo trading strategies" and land on lists of ten or fifteen ideas: moving-average crossovers, Bollinger Bands, pairs trading, market making. Most of those lists were written for stocks, forex or crypto. If you trade NIFTY or SENSEX options in India, a lot of what they cover does not apply to you, and the thing that does apply (selling options) usually gets one line.
So this page works differently. It gives you a straight answer on what counts as a strategy, a map of the families with an honest verdict for an Indian index trader, the Indian rules that shape any strategy in 2026, and a way to build and test one. Where we have written a full page on a mechanic, it links there. Everything here comes from how we run an expiry-day option-selling desk, so it is one practitioner's view, not a survey of the whole field.
Short answer. An algo trading strategy is a fixed set of rules for entry, size and exit that software follows without second-guessing. The software adds speed and discipline. It does not add an edge. For NIFTY and SENSEX, the family that fits is option selling, because index options usually price in more movement than the index delivers. That edge is thin, it comes and goes, and it only survives with strict stops and sizing. Paper trade any of it first.
If you are new to the subject, read the complete guide to algo trading in India first, since it covers how execution, broker APIs and automation fit together. This page assumes you know what an algo is and want to know what to run on it.

What actually counts as a strategy
Three different things get called "algo trading", and mixing them up is the most common mistake we see in beginner questions.
- The strategy is the decision logic: sell a strangle at 9:30, stop each leg at a set multiple, close everything by 15:15. You could run it by hand.
- The execution algo is how an order gets filled. VWAP and TWAP split a large order into slices so you do not move the price. They have no opinion on direction, so they will never generate a trade on their own.
- The platform is the software and broker connection that carries the rules out. Tradetron, AlgoTest, Streak and a Python script on a broker API are all platforms. Choosing one is a separate decision, covered in our algo trading software comparison.
When a vendor says "our algo makes 3% a month", ask which of the three they mean. Usually it is the platform, and the strategy inside is whatever you bring to it. We go further on this split in what algo trading is, option selling versus momentum.
The strategy families, and which ones matter to an Indian index trader
Here is the map. Roughly half of these are real strategies a retail or small prop desk can run. The other half are execution techniques, institutional games or research projects that get listed beside them anyway.
| Family | What it does | What usually breaks it | Fit for a NIFTY/SENSEX option trader? |
|---|---|---|---|
| Option selling (short straddle, short strangle, iron condor, credit spread) | Sells premium and collects time decay, with a stop on each leg and adjustment rules | Gap days and fast one-way moves. Losses are rare but large, so sizing and stops decide everything | Yes. This is the whole second half of this page. It is the only family EliteAlgo runs for clients. |
| Time-based entries (the "9:20 straddle" style) | Enters at a fixed clock time, usually at-the-money, with fixed stops. No indicator involved | Crowding. When thousands of accounts enter the same strikes at the same minute, fills get worse and the premium you are paid for shrinks | Yes, and it is a legitimate option-selling design. Test the exact entry minute and the fill model before trusting any popular version of it. |
| Trend following / breakout | Trades in the direction of a confirmed move: moving-average crossovers, Donchian breakouts, MACD and ADX filters | Sideways, choppy markets. Many small losses and a low hit rate by design | Indirectly. Useful as a regime filter, since a strong trend day is when a short strangle hurts most. See the NIFTY and SENSEX algo trading guide. |
| Mean reversion (Bollinger Bands, RSI, z-score) | Takes counter-trend positions when price stretches too far from a reference level | A real trend. The strategy keeps fading a move that never comes back | Indirectly, for the same reason. A reverting index is a friendly place for a seller; a trending one is not. |
| Momentum / factor ranking | Ranks stocks by recent returns, quality or volatility and holds the leaders | Sharp reversals and crowded trades | No. It is a stock-portfolio strategy, not an index-option one. |
| Statistical arbitrage / pairs | Trades the spread between two related instruments back toward its average | A relationship that stops holding. Correlation is not the same as a spread that reverts | No. Different instruments, different capital and different infrastructure. |
| Cross-venue arbitrage | Buys on one venue and sells on another to capture a price gap, for example the same stock on NSE and BSE | Latency and costs. The gap is a few paise and closes before a retail order arrives | No. This is a co-location game. |
| Index rebalancing | Positions ahead of forced buying or selling when a stock joins or leaves an index | Crowding and front-running by faster players | No. Retail platforms rarely support it and the edge is small. |
| Market making | Quotes both bid and ask and earns the spread while managing inventory | Adverse selection and stale feeds. Needs speed and exchange-grade infrastructure | No. |
| ML, neural nets, sentiment signals | Predicts direction or classifies regimes from many inputs, including news text | Overfitting, look-ahead leakage and models that cannot be explained when they fail | Not as a starting point. High accuracy on a prediction does not mean profit after costs. We do not run anything we cannot explain. |
| VWAP / TWAP execution | Slices a large order to reduce market impact | Rigid slicing can miss better prices | Not a strategy. It is how you fill a decision you already made. |
That table is why this page is a hub and not a single long essay. Three thousand words on pairs trading would not help anyone who came to sell NIFTY options, and it would not be honest about what we do all day.
The desk notes: one page per mechanic
Each of these is a single question we had to answer on our own desk before we trusted a rule in a live algo. They are written as findings, not introductions: where the common version of the idea is wrong, what we measured instead, and what rule we kept.
Option chain analysis — the six columns that matter
Most of the NIFTY option chain is noise to a seller. This one covers the six columns we actually read, the order we read them in, and the bid-ask spread math that changes which strike we end up selling.
Read first if you are picking strikes by hand.
The ATM straddle chart as a decay clock
The combined ATM call-plus-put premium is the cleanest single read on whether decay is being paid out or clawed back. Four recurring shapes, what each one means, and how the shape changes on expiry day.
Read second — it frames everything below.
The expiry-day premium clock, hour by hour
Expiry day is not one straight decay line. Premium re-prices in the opening half hour, drifts mid-session, accelerates after lunch, then turns into a gamma problem. The hour-by-hour map, with a paper-trade session template.
Read before you set any expiry-day entry time.
Greeks on expiry day — theta stops, gamma starts
Theta looks like the whole trade until the gamma crossover arrives, usually around 13:30 IST. Our own delta walk through an expiry session, a stop-loss comparison, and the three rules that fall out of it.
Read with the premium clock — they are the same story from two angles.
PCR — why the 0.7 and 1.3 rulebook breaks
The 0.7-oversold / 1.3-overbought bands were never calibrated on NIFTY. Where the ratio's arithmetic falls apart specifically on expiry day, and the narrow job it still does on our desk as a gate rather than a signal.
Read if you are using PCR as an entry trigger.
Open interest without the folklore
The four-box "long buildup / short covering" table everyone copies cannot tell you who initiated a trade — the data simply does not carry that. What OI does measure, and the liquidity and crowding reads that survive scrutiny.
Read alongside the option chain note.
Max pain — testing the pin everyone quotes
Every dashboard prints a max-pain strike with an arrow implying price is headed there. We hand-calculated it, tracked it intraday, and measured 40 expiries to see how often the close actually lands near it.
Read before you trust any pin-risk claim.
If you want a reading order rather than a grid: start with the option chain columns, then the straddle chart, then the premium clock and expiry-day Greeks together. The last three, PCR, open interest and max pain, are all about the same mistake: treating a derived number as a direction signal when it is at best a gate.
What EliteAlgo actually runs
One family, two indices. Rule-based and quant-based option-selling strategies on NIFTY 50 and SENSEX, with a primary focus on expiry-day sessions. No discretionary overrides, no black-box signal we cannot explain, and a hard stop-loss on every leg before the position goes on.
Why option selling specifically: index options tend to price in more movement than the index goes on to deliver, and the gap between implied and realised volatility is what a seller is paid for. That edge is real but thin. It is not present every day, and it disappears without position sizing and stop discipline, which is why most of our research time goes into the exit rules rather than the entries.
The structures, side by side
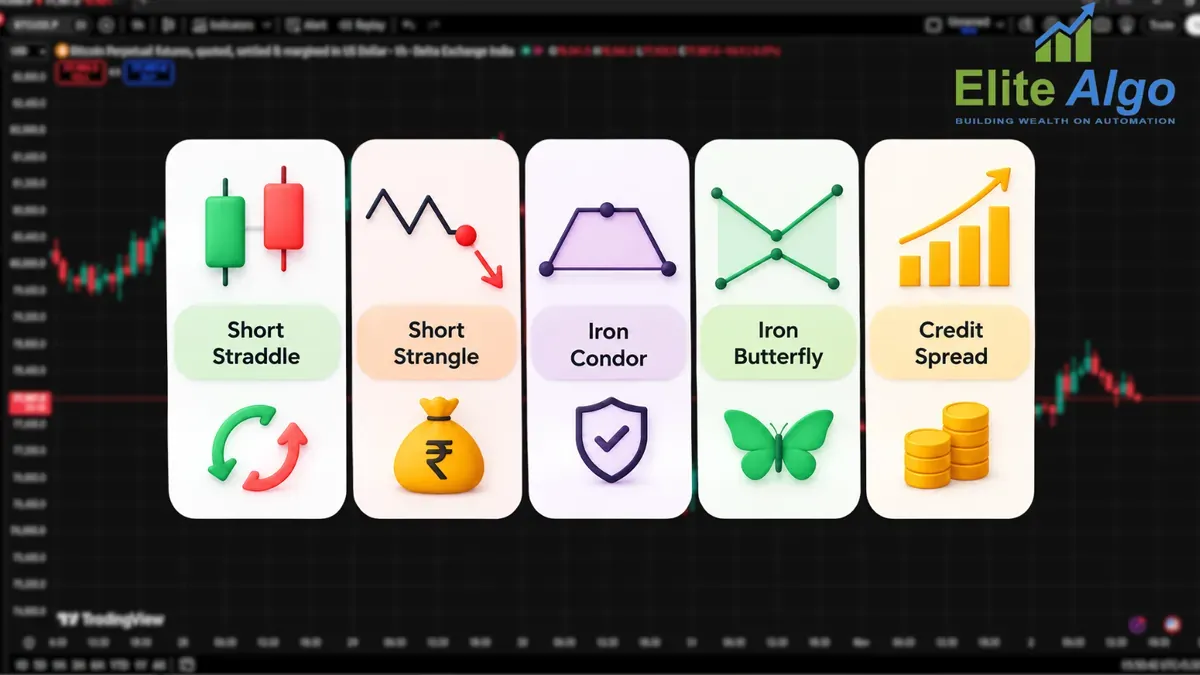
"Option selling" is a family, not one trade. The structures differ in what they risk and what they cost to run, and the legs matter more than people expect: every leg is another fill, and every fill is another slice of slippage.
| Structure | Legs | Risk shape | What to know before you automate it |
|---|---|---|---|
| Short straddle | 2 (call and put at the same strike) | Highest premium, highest sensitivity to a move in either direction | Concentration risk is real. See short straddle explained and why many accounts selling the same straddle is a risk. |
| Short strangle | 2 (out-of-the-money call and put) | Lower premium, wider break-evens, still open-ended loss | Compare the two in straddle versus strangle on NIFTY. Margin is the constraint: SPAN and exposure on a strangle. |
| Iron condor | 4 (strangle plus bought wings) | Defined risk, but you pay for the wings every cycle | Defined risk changes the shape of the loss, not its sign. We explain why we trade one and not both in iron condor versus naked strangle. |
| Iron butterfly | 4 (straddle plus bought wings) | Defined risk with a narrow profit zone | Four fills per entry. See butterfly and iron butterfly for option sellers. |
| Credit spread | 2 (sold and bought strike on one side) | Defined risk, directional view | See when we cap risk instead of selling naked and how we hedge a naked strangle. |
Starting points if option selling is the part you came for: the NIFTY option selling guide for beginners, the SENSEX weekly expiry approach, the broader option selling strategies explained, and what we run for clients. If you are weighing selling against buying, read option buying versus option selling first. Paper trade any of it first. Every rule on this site was paper-traded before it was funded, including the ones that looked obvious.

The Indian rules that shape any NIFTY or SENSEX strategy in 2026
Generic strategy lists skip this part, and it changes what you can run.
- One weekly expiry index per exchange. Since 20 November 2024, SEBI's rules let each exchange keep weekly contracts on only one benchmark index. NSE kept NIFTY 50, which now expires on Tuesdays. BSE kept SENSEX, which expires on Thursdays. Bank Nifty, Fin Nifty and Midcap Nifty moved to monthly expiries. If an older strategy write-up builds around a weekly Bank Nifty expiry, it is describing a market that no longer exists. Zerodha's support note on the discontinued weekly expiries has the list. When the expiry day is a holiday, the expiry moves earlier, so check the exchange calendar rather than assuming the weekday.
- Retail algo framework, fully applicable since 1 April 2026. Orders from an algo carry a strategy ID, a self-coded algo runs from a static IP registered with your broker, and above the exchange's order-rate threshold an algo has to be registered with the exchange. What each of those means in practice is on our SEBI algo trading regulations page. Because the framework runs through brokers, your choice of broker API now limits what you can run. See algo trading broker APIs in India and the Zerodha, Fyers and Angel One API comparison.
- Costs are part of the strategy. STT on options falls on the sell side, so a premium-selling book pays it on every entry. Read what sellers get wrong about STT and how options trading is taxed in India before you trust a gross backtest number.
- Position size is set by lot size and margin, not enthusiasm. Contract sizes get revised by the exchanges from time to time, so look up the current lot size on the NSE or BSE contract page before you size anything. Our NIFTY lot size and position sizing page shows the method.
EliteAlgo is analytical software, not investment advice. We describe rules and how they behave. We do not tell you what to trade. See the difference between a research adviser and analytical software for what that means for you as a reader.
How a strategy gets built and tested
Every competitor page has some version of the same five steps, and they are right as far as they go. Here is how they look when the strategy is a short-option expiry system.
- Write down a hypothesis you could be wrong about. For example: "a strangle sold at a set time on expiry day, stopped at a fixed multiple of premium, earns more than its costs." A sentence like "RSI works" is not a hypothesis.
- Turn it into exact rules. Entry minute, strike selection, stop for each leg, a time exit, and what happens if a leg is stopped early. If a rule needs your judgement, it is not a rule yet. Our trailing stop-loss for short options note shows how much a single exit rule changes.
- Backtest it with honest fills. Options fills are not at the mid price. Apply brokerage, STT, exchange charges and slippage per leg. Enter on the next candle after the signal, not the one that created it. The limits of the exercise are in what a backtest can and cannot prove, and the working method is in how to backtest an option-selling strategy. For tooling, see options backtesting software for India and where to get NSE historical options data.
- Paper trade it live. A backtest cannot show you API behaviour, rejected orders or what the spread does at 14:45. The routine we use is in paper trading an option-selling algo.
- Go live small, and keep the review loop. One lot, a written kill rule, and a weekly check of live results against the backtest. If you code the rules yourself, Python for algo trading in India covers the stack.
What our own records say about this
We would rather show you where this process has not worked for us than wave at "backtest and optimise". Two samples from our own record, both published in full on our own-data page:
- We tested the very common idea of taking a technical signal on the index and selling options against it. Across 438 trading days, selling a short strangle on the signal lost roughly Rs 499 per lot per day, even with slippage set to zero. The iron condor version lost more. None of eighteen structure-and-parameter combinations cleared our acceptance gate. Automation ran the rule faithfully, and the rule had no edge.
- Across 163 logged expiry sessions of the structures we do run, the median session gave back 42.8% of its intraday profit peak by the close, and roughly 30% of sessions closed as a loss after being profitable earlier in the day. The exit is not a detail in this style of trading.
Those numbers describe what these specific configurations did on those specific days. They are not a track record, not a projection and not advice. We include them because a strategy page that only shows what worked is showing selection, not performance.
Choosing between them
Three questions decide it, in this order.
- What does a bad day look like to you? Trend and momentum strategies lose in many small, frequent, visible ways. Option selling loses rarely and then badly. The distribution is lumpy, and the lumps arrive on gap days. Pick the shape of loss you can actually sit through, because you will sit through it.
- How much capital, and is it margin-capable? Option selling is a margin business, and the NIFTY/SENSEX strategies we run for clients need serious capital behind them. Below that, paper trading and a single-lot learning account are the sensible path, not a scaled-down version of an institutional strategy.
- How much attention can you give it? "Automated" does not mean unattended. Budget 30-60 minutes a day for monitoring and exception handling, plus a few hours a week for review. If that is not available, a managed arrangement is the honest answer rather than a half-watched algo. See our managed service.
Where to get a strategy: build it, buy it, or have it run for you
There are three routes in India, and each one fails in its own way.
- Build it yourself on a no-code builder or a broker API. You control the rules and you own the testing. The cost is your time, and the risk is fooling yourself with a flattering backtest.
- Subscribe to a marketplace strategy. Several brokers and research desks list ready-made algos with performance curves and a minimum capital figure. That is convenient, but those curves are backtests unless the page shows a dated live record. Ask the five questions in the FAQ below before you put money behind one. Also check that the minimum capital shown covers the margin the position really needs.
- Hire a managed service. Someone else runs the rules and watches the book. You still carry the market risk and you still need to understand the strategy. Judge the provider on how they disclose losing periods, not on how many winning ones they show.
Copying someone else's trades is a fourth route that looks like a shortcut. What copy trading actually copies in option selling explains why the copy rarely matches the original once fills and timing differ.
Before any of it goes live
Backtesting is where most strategies die, and it should be. The rules that matter:
- At least three years of data. A strategy needs to survive more than one volatility regime, and for weekly-expiry options the weekly contract history is shorter than that, so say so out loud and discount the result accordingly.
- Realistic costs. Brokerage, STT, exchange fees and slippage, applied per leg, not as a single round-trip guess.
- Out-of-sample testing. Test on data the parameters were never fitted to. Never optimise in-sample and deploy the same week.
- Walk-forward analysis. Roll the optimisation window forward and test on the next window. It is slower and far harder to fool yourself with.
- Parameter count discipline. Past five or six tuned parameters, you are describing history, not finding an edge.
- Report the failures too. Count how many variants you tried against how many survived. One winner out of an unstated number of attempts is a selection result.
Platform choice for this is covered separately in our algo trading software comparison. If you prefer to compare a simulator with a proper test, read option simulator versus backtest.
Risk rules we treat as non-negotiable
These have not changed since 2006, through several market cycles, and they are deliberately boring:
- Position sizing: no single trade risks more than 1-2% of total capital
- Strategy-level drawdown limit: a strategy more than 10-15% below its own high gets paused and reviewed, not "given a chance to recover"
- Circuit-breaker halt: all strategies stop if the index moves more than 3-4% inside 30 minutes
- Diversification: 3-5 genuinely uncorrelated strategies, where uncorrelated is tested rather than assumed
- Daily loss limit: hard stop on the whole book at 3% portfolio loss for the day
Two more things worth reading before you commit capital: the disadvantages of algo trading, which is the page we point sceptical clients at first, and the zero-risk option strategy myth, which explains why no structure removes risk and only moves it somewhere else.
Frequently asked questions
What is an algo trading strategy?
Which algo trading strategies are used in India?
Which is the best algo trading strategy for NIFTY?
Is algo trading legal for retail traders in India?
What is the difference between a strategy and an algo?
Can I run algo strategies on NIFTY and SENSEX weekly options?
How much capital do I need to start?
Should I buy a strategy from a marketplace?
EliteAlgo provides analytical software and rule-based execution, not investment advice. All trading carries risk and past performance does not indicate future results.